The Financial Truth Behind the Russo-Japanese War: Why Russia Lost the War of Wallets

The Russo-Japanese War was decided not on the battlefield but in international credit markets.
Historian Sarah Paine argues that the true deciding factor in the Russo-Japanese War was international credit, not military outcomes. Japan's battlefield victories steadily improved its credit rating, reducing borrowing costs and securing key loans after Mukden that kept it financially afloat despite stretched manpower. Russia, by contrast, entered the war on already shaky fiscal ground after a pre-war recession and crop failure; Mukden's defeat shattered creditor confidence, trapping Russia in a vicious cycle of defeat, lost creditworthiness, and dried-up financing. The Treaty of Portsmouth followed — and the only loan Russia secured afterward was used not to fight, but to bring its troops home.
Historian Sarah Paine, in a recent interview, raised a point that is often overlooked: the outcome of the Russo-Japanese War was determined less on the battlefield than in the international credit markets. Russia's eventual decision to seek peace came down, at its core, to an inability to keep paying for the war.
The Credit Logic Behind the War
Both Japan and Russia relied on external loans to sustain this extraordinarily costly conflict. Paine argues that the war was prohibitively expensive for both sides, and whoever could maintain access to financing could keep fighting.
The critical dividing line was how battlefield performance affected the cost of borrowing. Japan's string of military victories steadily improved its credit rating in international markets — the interest rates it paid on loans kept falling. Borrowing remained expensive for Japan, but the declining rates meant it could continue raising war funds at an increasingly manageable cost.
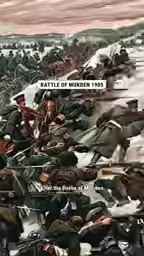
This was a classic positive feedback loop: battlefield victories boosted creditworthiness, improved credit lowered borrowing costs, and lower costs allowed the war to continue. Paine specifically notes that Japan secured its final two loans after the Battle of Mukden, leaving it financially prepared to fight on.
This model of war financing was fairly common during the late 19th to early 20th century "age of imperialist wars." The major powers had not yet developed large-scale mechanisms for selling government bonds domestically, and wartime military spending depended heavily on private capital markets centered in London, Paris, and New York. During the Russo-Japanese War, Japan's primary loan underwriters were Anglo-American bankers — most notably Kuhn, Loeb & Co. under Jacob Schiff, who actively backed Japanese war bonds out of opposition to the Tsar's antisemitic policies. This meant international credit was far from a neutral financial transaction; it was entangled with geopolitics, ideology, and ethnic sentiment. The subjective judgment of creditors mattered just as much as a debtor nation's performance on the battlefield.
Japan: Short on Soldiers, Not on Money
Paine offers a striking observation: Japan did not actually have enough manpower to fight the war to a decisive finish — but it had assembled enough financial resources to keep going.
In other words, Japan's military manpower was approaching its limits, but the trust of international capital provided a crucial safety net. This state of being "financially solid but militarily stretched" illustrates that modern warfare is a competition of comprehensive national power, in which fiscal resilience matters just as much as military strength. The ability to secure the next loan directly determined whether a country could drag the war into its next phase.
Russia: Financially Strained Before the War Even Began
In sharp contrast to Japan, Russia's financial troubles were baked in long before the first shot was fired.
Paine notes that Russia experienced an economic recession the year before the war, compounded by a devastating harvest failure, which severely damaged government revenues. Russia's economic foundation throughout the entire conflict was therefore shaky from the start. The war only amplified an existing financial vulnerability — it was not the sole cause of the collapse.
After Mukden, No One Would Lend to Russia
The turning point came, once again, after the Battle of Mukden. When Russia urgently needed a new loan to sustain the war effort in the aftermath of that decisive engagement, it found the international markets unwilling to oblige.
The reason was straightforward: creditors no longer viewed Russia as a sound investment. Battlefield defeats had destroyed Russia's creditworthiness, and the collapse of its credit cut off the funding it needed to continue fighting. This was the mirror image of Japan's positive feedback loop — Russia was trapped in a vicious cycle of defeat, lost credibility, and dried-up financing.
The Battle of Mukden (February–March 1905) was one of the largest land battles of the industrial era, with over 600,000 troops engaged on both sides along a front stretching roughly 150 kilometers. Russian forces ultimately suffered around 90,000 casualties and were forced to retreat northward — a catastrophic blow to the prestige of the Tsar's army. Just three months later, the Battle of Tsushima (May 1905) all but annihilated Russia's Baltic Fleet. These two consecutive decisive defeats convinced international creditors that Russia was incapable of reversing the tide of war, and that continuing to lend would be throwing money into a bottomless pit. This is the core logic of sovereign credit assessment: lenders evaluate not just a nation's current ability to repay, but its future probability of survival and its will to honor its debts.
The Tsar's Empty Piggy Bank
Paine summarizes this chapter of history with a vivid metaphor: Nicholas II's "piggy bank" had run dry, and so he had no choice but to call off the war.
A particularly ironic detail: after the Treaty of Portsmouth was signed, Russia did manage to secure one more loan — but the funds were used solely to transport troops stranded in Asia back to European Russia. In other words, the last money Russia borrowed was not for fighting, but for the logistics of retreat.
This analysis reveals another dimension through which to understand the war's conclusion. The outcome of individual battles certainly mattered, but what truly determined whether a great power could hold on was the financial capacity and international credit standing behind it. The end of the Russo-Japanese War was written less on the battlefield than in the credit markets.
The Treaty of Portsmouth was signed in September 1905, brokered by U.S. President Theodore Roosevelt. Russia renounced its privileges in Manchuria and ceded the southern half of Sakhalin Island to Japan, but refused to pay war reparations — itself a reflection of Russia's extreme financial distress. The loan Russia obtained on French markets after the treaty was signed is generally identified as the Franco-Russian Loan of 1906, totaling approximately 2.3 billion francs — one of the largest sovereign loans in history up to that point. The funds were used partly to stabilize domestic political turmoil stemming from the Revolution of 1905, and partly, as Paine describes, for the military withdrawal. The symbolism is hard to miss: Russia regained its ability to borrow precisely at the moment it abandoned its wartime ambitions. Peace, in the end, was what rebuilt its credit.
Related articles

Beyond the Mainstream World: Security and Privacy Struggles in Overlooked Regions
Human-centered security research has long focused on the West, causing security solutions to fail in the mainstream world. Researcher Collins Minando draws on Kenyan mobile loan apps, internet café authentication dilemmas, and local expert studies across nine countries to reveal how socioeconomic constraints reshape privacy practices, and proposes mobile money privacy redesign and PETs deployment pathways.

Claude Reportedly Able to Hide Secret Messages in Benign Images
A Reddit post claims Claude Fable 5.1 can hide secret messages in benign images. This article reviews the background, image steganography principles, and potential security risks, and suggests a testing path from rumor to verification.

Federal Government Awards $85 Million; CFS to Develop Fusion-Specific Semiconductors
The federal government awards $85 million to Commonwealth Fusion Systems to develop conductors and power semiconductors for fusion plants. This article analyzes the significance of this funding for the fusion supply chain and commercialization path.