Anthropic's $2 Trillion Valuation Deconstructed: Why the AI IPO Wave Keeps Faltering

The Nasdaq is at an all-time high, and a purchasing managers' survey shows U.S. business output growing at its fastest pace in five years. By all logic, this should be a golden window for tech companies to go public. Yet the reality is that a string of AI-related IPOs are quietly being withdrawn or delayed.
Jay Ritter, who runs the IPO research program at the University of Florida, told Bloomberg: "To have this happening against the backdrop of the Nasdaq at a record high is especially surprising."
Anthropic was originally expected to publish its public listing filing materials as early as the end of August, but nothing has appeared. OpenAI has pushed its IPO plans to next year. SoftBank-backed data center developer SB Energy filed its paperwork before Labor Day but has yet to launch its share marketing. After Labor Day, only three IPOs have been completed across the entire market, and five of this year's ten largest listings have already fallen below their offer price.
Then again, Anthropic is seeking a valuation of roughly $2 trillion. As The Economist noted, that figure is roughly equal to the combined valuations of the ten largest tech IPOs in history.
Why does Nvidia, the shovel seller, look cheap, while Anthropic, digging for gold with a shovel, wants $2 trillion?
How Is the $2 Trillion Valuation Calculated?
Investment bank valuations typically use two methods: the discounted cash flow model (projecting future cash flows and discounting them to the present), and reference multiples from comparable listed companies. After running the numbers, companies launch a roadshow and finalize the offer price based on investor orders. Those massive spreadsheets mostly exist to make the final quoted number look grounded in reality.
But both methods run into trouble with Anthropic. There are no comparable listed companies in the market, and the company's revenue has grown more than tenfold in a year, making cash flow forecasting itself extremely difficult. In August its annualized revenue was around $65 billion, and the FT's Lex column warned that these unofficial circulating figures must be treated with particular caution.
The discounted cash flow model also requires an interest rate. After that very same survey showing a booming economy came out, the U.S. 10-year Treasury yield climbed to 5.23% on Thursday evening, a high not seen since 2004.
Matt Kennedy of Renaissance Capital told Bloomberg that rising rates deal a double blow to companies like this: first, they reduce the present value of profits the company won't earn until years from now; second, the financing cost of borrowing money to build data centers also rises.
The core idea of the discounted cash flow model (DCF) is that a company's value equals the sum of all its future years' free cash flows discounted to the present at some discount rate. The discount rate reflects the time value of money—a dollar received today is worth more than a dollar received ten years from now, and the difference is captured by the discount rate. In practice, the 10-year Treasury yield is often used as the benchmark risk-free rate, with an equity risk premium layered on top. When the risk-free rate rises from 2% to 5%, the discounted present value of the same future cash flows shrinks substantially, and the longer the duration of the asset, the harder it is hit. This is precisely why AI labs—whose profits lie almost entirely in the distant future—are so sensitive to interest rates: nearly all of their value comes from cash flows ten or more years out, and every percentage point rise in the discount rate cuts the valuation by a large margin.
TAM (Total Addressable Market) refers to the total revenue a product or service could theoretically generate if, under ideal conditions, it captured every potential customer. It's typically used by companies to illustrate "how high the growth ceiling is," but in IPO narratives it is easily exaggerated: TAM can be redefined by the broadest possible framing of industry boundaries, counting adjacent markets and even demand that doesn't yet exist. TAM itself does not equal the revenue a company will actually capture; the share a company ultimately wins (i.e., penetration) is often only in the single digits. During the dot-com bubble, a large number of companies used sky-high TAMs to support valuations; Uber's advertised $122.3 trillion TAM at its 2019 IPO is a classic example, and its actual annual revenue remains far below that order of magnitude to this day. The essence of TAM inflation is grafting macro-level imagined potential directly onto a single company's equity pricing.
The McNealy Test: The $2 Trillion Valuation Fails the Rational Pricing Check
After the dot-com bubble burst in 2002, Sun Microsystems co-founder Scott McNealy explained to BusinessWeek just how absurd it was that the market had valued his company at ten times revenue at the peak of the bubble.
He said at the time: if the valuation is ten times revenue and you want to recoup your money in ten years, the company would have to pay out its entire revenue to shareholders as dividends for ten consecutive years—which would require shareholder consent, zero cost of goods sold, no operating expenses whatsoever (but the company had 39,000 employees), zero corporate taxes, and no taxes on the shareholders receiving the dividends. Even if every one of those conditions were met, who would still be willing to buy the stock at $64 a share?
McNealy was actually being lenient—he didn't factor in the time value of money. At the peak of the bubble in early 2000, the 10-year Treasury yield was about 6.5%. At that rate, a dollar received ten years later is worth far less than a dollar today. Even with zero costs, zero taxes, and zero R&D spending, an investor buying at ten times revenue would still not recoup their money in ten years—it would take roughly 17 years.
If Anthropic reaches a $2 trillion valuation, that corresponds to roughly 31 times revenue. Set the conditions even looser than McNealy did—assume Anthropic has no costs, doesn't need to hire employees, pays no taxes, pays no electricity bills, pays out every penny it earns to shareholders in perpetuity, and applies no standard risk premium, discounting directly at the Treasury yield—even if every one of those assumptions held, investors would never recoup their principal. Forget 10 years; not even 100 years would do it.
Discounting all of its future revenue back to today yields a value of roughly $1.27 trillion, still $730 billion short of $2 trillion. In other words, almost the entire $2 trillion valuation is a bet on future growth. The higher rates go, the more astonishing the growth it must deliver.
Conventional math can't produce the number $2 trillion, so a different logic has to be brought in.
TAM Inflation: A Numbers Game from $22.7 Trillion to $60 Trillion
TAM, short for Total Addressable Market, refers to the total revenue a company could capture if it took the entire industry. The metric has long existed, but it truly became popular in the late 1990s, when internet analyst Henry Blodget used this logic to argue that Amazon, then trading at $240 a share, deserved to be worth $400 a share—and Amazon's stock did indeed hit that level within just a few weeks. Blodget became famous overnight, and was later banned from the securities industry for life.
The FT's Lex column traced how these numbers have inflated across the AI industry. In May, Musk told investors that the enterprise applications market, including his own AI products, was worth $22.7 trillion—roughly three-quarters of the entire U.S. economy. Last week Morgan Stanley estimated that the market generative AI could tap reaches $60 trillion, nearly half of total global annual output. Lex noted that Morgan Stanley is very likely serving as an underwriter for Anthropic's IPO—though that is almost certainly just a coincidence.
In just four months, the addressable market grew by $37 trillion out of thin air, a pace far outpacing Anthropic's own revenue growth and far exceeding the growth rate of the global economy it hopes to carve up.
However vast the TAM a company's valuation leans on, the share it actually captures is often minuscule. Uber trumpeted a $122.3 trillion TAM at its 2019 IPO, yet its annual revenue today is still under $1.3 trillion—meaning 99.5% of the market remains untapped. WeWork claimed a $3 trillion addressable market and ended up bankrupt.
Anthropic's internal research unit has even modeled an extreme scenario: by 2030, AI could add more than $10 trillion to U.S. GDP. Lex roughly calculated that this would correspond to a present equity value of $100 trillion.
How Far Is AI Self-Improvement from Reality?
Even more fantastical is recursive self-improvement—AI designing stronger AI, which iterates into an even more capable generation, creating enormous economic value until money and asset pricing lose all meaning. Musk has predicted that AI and robots will make work optional and money meaningless.
How far is recursive self-improvement from reality? Last year Google DeepMind's AlphaEvolve found a matrix multiplication algorithm that outperformed a traditional method in use for 16 years. But in a research review video on the House of LayE YouTube channel, run by a computer scientist with a PhD, it was noted that all these impressive results were set up with a clear scoreboard and a known correct answer as the test target. Anthropic's own automated research tool closed a task-performance gap by 97%, but some of that came from exploiting loopholes in the experimental rules; when the approach was scaled up, the performance gain was only 0.5 percentage points, already within the margin of experimental error. To be fair, Anthropic itself published this disappointing data, which already puts it ahead of the vast majority of companies.
Back in reality, 18 months ago Anthropic predicted its 2027 revenue could reach $12 billion—relatively conservative amid a sea of optimistic forecasts. But by August of this year, valuation authority Aswath Damodaran raised the question on a podcast: as the halo fades, might Anthropic's valuation expectation be revised down from $1 trillion to $800 billion? Yet just seven weeks later, the target valuation being discussed in the market had become $2 trillion.
Recursive self-improvement is a core concept in AI safety and intelligence explosion theory, referring to an AI system's ability to improve its own code or design the next generation of AI, with the stronger generation further accelerating iteration, forming a positive feedback spiral. In theory, this process could bring rapid leaps in intelligence—the so-called "singularity." But in reality there is still a vast distance between AI research tools and true recursive self-improvement: current systems mostly optimize within clearly defined goals, scoring standards, and experimental frameworks set by humans; once removed from the given scoreboard, their ability to generalize in open environments drops sharply. The data Anthropic published illustrates exactly this—a 97% reduction in performance gap looks astonishing, but part of it comes from exploiting experimental loopholes, and the scaled-up gain is only 0.5 percentage points. This shows that current AI is better at finding optimal solutions within established rules than at independently defining problems and goals. Treating recursive self-improvement as a valuation basis that can be realized within a few years is essentially discounting a highly uncertain theoretical possibility into present equity premium in advance.
Why Is a Data Center That Isn't Even Built Worth $50 Billion?
This AI boom has also invented a method for valuing buildings that aren't yet built.
SoftBank-backed U.S. data center developer SB Energy hopes to secure a valuation of about $50 billion after going public. What makes this company unusual is that it doesn't yet have a single data center in formal operation. Lex noted that SB Energy has never built a data center itself; it recently acquired a consulting firm that has participated in building 15 data centers.
At a $50 billion valuation, SB Energy would trade at 400 times EBITDA. Its own prospectus shows that completing the construction projects it has already committed to will require another $174 billion in investment. On Thursday its new bond issue yielded 9.75%, setting a record for the largest junk bond issuance in history, with lenders requiring that the company not pay dividends before 2029.
Data centers still under construction are classified on the balance sheet as construction in progress and do not require depreciation charges. Jim Chanos made a similar point about Big Tech's GPUs: chips that have been purchased but not yet deployed also don't need to be depreciated. Seen this way, an unbuilt data center is almost the ultimate high-margin business—no electricity consumed, no maintenance needed, and customers won't complain about latency, since the product doesn't exist at all. The only problem is that sooner or later someone will press you to actually deliver.
And physical construction is where all the problems erupt. Lex cited the iron law of megaprojects proposed by Danish scholar Bent Flyvbjerg: over budget and over schedule are almost the norm. In some U.S. states, simply completing grid connection approval takes 10 years. A Gallup poll shows 71% of Americans oppose data centers being built near their homes. SB Energy's filing also flags the risk: if a project is delayed, customers can in some cases buy the project assets directly at a low price. Its primary customer is OpenAI.
Paul Kadrosky of Man Group said in a research note: lenders financing these projects reference long-cycle infrastructure like commercial real estate, but the chips installed inside become obsolete within a year or two—like taking out a 30-year mortgage to buy an iPhone.
Construction in progress is a line item on the balance sheet referring to fixed assets on which a company has begun work but which have not yet reached usable condition or completed final accounting. Under accounting standards, construction in progress is not depreciated until it is completed and transferred to fixed assets; only after it is formally put into use does amortization begin over its useful life. This leaves data center developers room for maneuver in both valuation and accounting: the later a project is completed, the later depreciation pressure appears, and the better book profits look. Chanos's skepticism about GPUs rests on the same internal logic—chips purchased but not yet deployed can temporarily avoid depreciation charges, temporarily inflating current profits. However, depreciation is only deferred, not eliminated; once projects are transferred to fixed assets en masse, depreciation expenses are released all at once, weighing on future profits. More critically, the economic life of chips is usually only one to two years, while the civil construction portion of a data center lasts for decades, creating a severe mismatch in depreciation schedules. Using the financing logic of long-cycle infrastructure to carry short-cycle chip assets is precisely the metaphor behind Paul Kadrosky's "30-year mortgage to buy an iPhone."
The Circular Loop: Who Is Actually Funding AI Infrastructure?
The funding logic here has a touch of circular closure.
SoftBank itself must bear junk-grade financing costs, and plans to issue more than $11 billion in new bonds to continue injecting capital into OpenAI; this bond issue also yields 9.75%. OpenAI is expected to burn close to $280 billion by the end of 2030, part of which is used to sign a 20-year lease with SB Energy for a large campus in Ohio—a lease that in turn provides SB Energy with the revenue supporting its valuation. OpenAI is also an investor in SB Energy, holding warrants—if SB Energy's valuation climbs to $80 billion, OpenAI can cash in the gains.
Then there's Nvidia. SB Energy's filing shows that in August Nvidia subscribed to $1.5 billion in shares at a 10% discount to the IPO price, and will invest another $1.5 billion during the IPO. Nvidia also provides up to $10.5 billion in guarantees for the Ohio campus; until OpenAI formally begins its lease in 2028, this guarantee will not appear as a liability on Nvidia's books. In exchange, the campus can only use Nvidia hardware for the next 20 years.
Simply put: SoftBank borrows at junk bond rates and uses the money to support OpenAI; OpenAI leases data centers; Nvidia guarantees the project; and the campus is fitted entirely with Nvidia chips. An interlocking set of transactions.
The Wall Street Journal reports that SpaceX provides computing services to Anthropic each month for $1.25 billion. In Amazon's latest earnings, 85% of net profit came from unrealized book gains on its Anthropic stake; 87% of Google's net profit came from gains on its SpaceX and Anthropic holdings. Aswath Damodaran lamented: he used to find valuing Asian family conglomerates the most headache-inducing, because valuing one company required first valuing four others; now, to value Microsoft, you first have to value OpenAI.
Across the industry, a默契 has formed: buying each other's products, guaranteeing each other's debt, and lifting each other's valuations.
Why Nvidia Is Actually Cheap
Nvidia is the company in this AI gold rush that genuinely sells tools, and its business is exceptionally strong. Bloomberg data shows that four years ago Nvidia's annual sales were $27 billion; this year they are expected to reach $410 billion, with net profit projected to nearly double. Yet against next year's expected profit, it trades at less than 17 times—a valuation at a low not seen in over a decade.
Nvidia CEO Jensen Huang said at a Goldman Sachs conference that Nvidia is the first and only stock in the world to combine growth and value characteristics, and that the market has seriously misunderstood the company. It's rare for the CEO of the world's most valuable company to actively pitch its own stock to value investors.
There are four logical explanations for why the market suppresses Nvidia's valuation.
First, the market treats Nvidia as a cyclical stock at the peak of the cycle. Last quarter its gross margin was 75%, but analysts expect it to fall below 72% by the end of this year, partly because Nvidia needs to source memory chips externally and memory chip makers are raising prices. Meta, Alphabet, and other largest customers are all developing their own competing chips. Cyclical stocks often look very cheap at peak profits, and investors choose to wait and see.
Second, Nvidia's revenue essentially equals the spending of other AI companies. A large share of that spending comes from AI labs that keep burning cash. TCW's Eli Horton told Bloomberg that Nvidia's current multiple only holds if AI spending slows. And the CEO of Anthropic has just publicly called for exactly that—slowing the pace of AI development. On the Monday after he published his article, the semiconductor index fell nearly 6% in a single day.
Third, uncertainty itself can push valuations higher. Analysts can already make rough predictions about Nvidia's revenue next year, but an AI startup lab could go bankrupt or could carve out a huge $60 trillion market. Finance scholars Lubos Pastor and Pietro Veronesi proposed that when a company's future earnings are highly uncertain, valuations are actually pushed up.
Fourth, the two are priced by completely different groups. Nvidia's stock price is determined by millions of investors trading in real time, including short sellers; Anthropic's valuation comes from multiple rounds of private financing, and many participants are themselves cloud providers, whose own book gains rise as Anthropic's valuation rises. The private market has no way to short it and hold it down.
The Price War and Intelligence Saturation
Why don't the major AI labs all slow down together? Because if you voluntarily decelerate, your technological lead narrows—and your peers won't stop with you.
The FT reports that low-cost open-source models from Chinese companies like DeepSeekAd and Moonshot are approaching the performance of top closed-source models. Just on Tuesday, Anthropic and OpenAI released price-cut versions of their products on the same day, with prices reduced 40% and 50% respectively versus the previous generation. A price war is good for consumers, but if you're about to launch an IPO, running into a price war is hardly ideal timing.
A new study from APOC AI calculates that since 2023, the cost required to achieve equivalent AI model performance has fallen 13-fold per year. The researchers say this decline outpaces the vast majority of revolutionary technologies in history, including electricity, computers, and DNA sequencing. At the same time, after a new top model is released, competitor prices quickly drop. APOC also points to a contradiction: the AI boom is driving up the prices of all upstream inputs—chips, electricity, even the labor cost of electricians—yet the price of AI output itself is falling rapidly. For chip sellers this is good news, but for businesses that make money by outputting AI capabilities, it's worth watching closely.
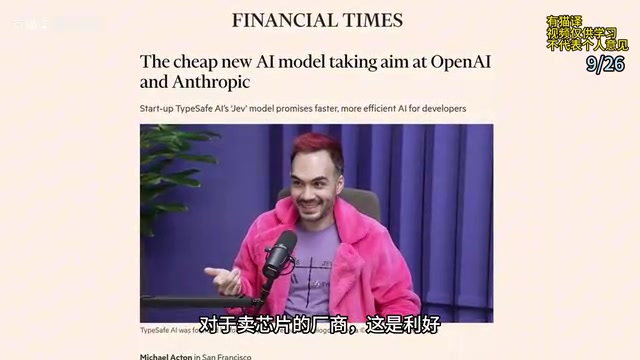
Last week a startup called TypeSafe AI released a model called J5, aimed mainly at software developers, who say that for simple decision tasks its cost can be as low as one four-hundredth of top closed-source models. The company has only raised a $40 million seed round. Eric Glyman, co-CEO of business payments company RAMP, told the FT that they use a routing system to assign different tasks to different models, cutting AI-related bills by 40%. He offered an analogy: you don't need to drive a Ferrari to buy groceries.
There are also defensible arguments for the AI lab bulls. User adoption of AI tools is indeed continuing to rise. Weekly call volume on the OpenRouter platform has surged 25,000% compared with early last year. Yale economics professor Ariel Telinsky found that among Anthropic's users, 22.5% are still using its models a year later, versus 13.2% for OpenAI. Damodaran believes Anthropic is one of the few AI labs that genuinely has direct-to-end-user revenue. Analyst Ben Thompson argues that if AI labs can both develop models and build accompanying software tools, they have a chance to lock in customers and protect profits.
But the model routing tools RAMP uses show that customers, too, are doing everything they can to avoid being locked in. AI labs may well succeed in building highly profitable business models in the future, but right now they want to sell shares to investors.
Model routing refers to using an intermediary layer system to dynamically allocate user requests to different AI models based on task type, complexity, cost budget, and latency requirements. Simple tasks go to cheap small models or open-source models, while only complex tasks call costly frontier closed-source models. The significance of this mechanism is that it breaks single-model lock-in: companies can ensure results while letting high-cost top models handle only a small number of critical tasks, thereby significantly cutting bills. RAMP's 40% reduction in AI-related spending through a routing system is direct evidence of this logic. For AI labs, model routing is a double-edged sword—it expands overall AI usage, but it also weakens the pricing power and customer stickiness of top closed-source models. When customers can switch tasks to cheaper alternatives at any time, the high valuation premium supported by "the strongest model" loses its moat. This is also the most direct contradiction between the price war and the valuation narrative.
When the Forest Falls, the Small Trees Go First
AI may very well reshape the entire world. The internet also changed the world, but in the early days of the internet wave, the market chased Yahoo, Lycos, and AltaVista for a long time before Google appeared. There's also another possibility: AI ends up like email—everyone depends on it, but it's hard to earn rich profits by selling the service.
An IPO is essentially a point at which a company and its early investors choose to cash out and exit, and it also puts all the assets in this circular loop into the public market for the first time to be priced for real. This carries hidden risk for SoftBank, whose balance sheet rests heavily on its OpenAI stake. Bloomberg reported in August that SoftBank borrowed $10 billion in margin loans using OpenAI shares as collateral. Going public can help SoftBank convert paper gains into real cash, but it will also set a fair market price for equity that has never traded publicly. If investors decide OpenAI isn't worth $852 billion, the value of the collateral in SoftBank's hands shrinks.
Anthropic's IPO is the first time a pure AI lab faces the public market's scrutiny, and the paper gains on Amazon's and Google's books will also face market pricing. Awkwardly, OpenAI controls the timing of its own IPO—Sam Altman told Fortune that given various current circumstances in the safety field, now is not the right time to go public. But other reports say OpenAI is negotiating a new private funding round at a target valuation of $1.2 trillion. Apparently $1.2 trillion is a price only suitable for sophisticated private investors.
Aswath Damodaran said: the dot-com crash wasn't one earth-shattering event, but tree after tree falling, until one day you wake up and find most of the forest has been destroyed. Withdrawn IPOs, elevated junk bond yields, and delayed filings may be the first small trees to fall. His advice to AI companies: show real data, don't just tell grand narratives. And a prospectus is the official document that forces companies to do exactly that.
On the other side, Wall Street is ready to sell shares aggressively. Jim Chanos expects this year's equity issuance could set a record. The conclusions of relevant academic research are not encouraging: Laun and Ritter's study shows that companies issuing large amounts of new stock tend to underperform the market in the following years; Baker and Wurgler found that when the market sees a large wave of new issuance, the overall market tends to perform weakly over the next few years. Insiders usually have a very good sense of when it's a good time to sell.
Investor Mike Paulos told the FT: AI lab CEOs call for slowing down and prioritizing safety, yet the market proves that the drive for profit overrides everything. Looking back in the future, we may regret not having taken their safety warnings seriously. But when it comes to selling shares, we should likewise trust the seller's true calculations.
If you enter at a $2 trillion valuation, even assuming zero costs, zero taxes, and no employees needed, the math still doesn't work. Once the investment ultimately falls short of expectations, someone will ask you the same question Scott McNealy asked in 2002: what on earth were you thinking?"}, "meta_description": "Anthropic seeks a $2 trillion valuation—equal to the ten largest tech IPOs combined. But soaring rates, withdrawn IPOs, TAM inflation, and circular financing are shaking the AI IPO pricing. Here's the logic gap, and why Nvidia is actually cheap.", "summary_oneliner": "The AI boom's valuation paradox: shovel-seller Nvidia looks cheap, while shovel-holder Anthropic wants $2 trillion.", "summary_paragraph": "As the Nasdaq hits record highs, a wave of AI-related IPOs is being withdrawn or delayed. Anthropic is seeking a roughly $2 trillion valuation—about 31 times revenue—which even assuming zero costs and zero taxes cannot be recouped when discounted at Treasury yields; conventional models simply can't produce the number. The article dissects the logics propping up that valuation: TAM ballooning from $22.7 trillion to $60 trillion in four months, a circular financing loop linking SoftBank, OpenAI, SB Energy, and Nvidia, and an unbuilt data center valued at $50 billion. Meanwhile Nvidia trades at under 17 times forward profit, a decade low. AI model costs fall 13-fold per year, the price war escalates, and cheap open-source rivals erode top-model premiums. The author warns: withdrawn IPOs and elevated junk bond yields may be the first small trees to fall before the forest collapses.", "seo_keywords": ["Anthropic valuation", "AI IPO", "2 trillion valuation", "Nvidia valuation", "TAM inflation", "AI bubble", "circular financing", "discounted cash flow\
Related articles

How Big Can Stars Really Get? The Physical Limits of the Largest Stars
Red supergiants are the largest stars by volume, with radii up to 2,000 times the Sun, engulfing the inner solar system. But there is no precise upper limit on stellar size—models predict up to 15,000 solar radii. The most massive blue stars are far smaller than red supergiants—biggest and heaviest are two different things.

Apple HomeView Smart Display Full Feature Breakdown: Wall-Mount or Desktop, $299
Apple launches HomeView, a $299 smart display with wall-mount and desktop options, 12MP camera for facial recognition, smart home control, music playback, and recipe step-by-step cooking. Full breakdown of watch faces, apps, privacy, and cooking integration.

Where Did the Promised New Studio Go? Craft Computing Answers After Five Years
Craft Computing's host responds to viewer questions: the new studio promised five years ago was shelved as construction costs soared from $30,000 to $75,000, and was replaced by a 168-square-foot garage conversion.