Paraguay Bank Collapse Wipes Out Half the Population's Savings: A Financial Risk Perspective Through AI

A bank collapse in Paraguay involving half the population's savings exposes systemic financial risk and the space for AI early warning.
Starting from a Hacker News discussion about a bank collapse in Paraguay, the article notes that half the country's population has savings concentrated in one bank—a failure would trigger bank runs, consumption contraction, and chain reactions in the real economy. The author argues this is exactly where AI can add value in financial risk monitoring: anomaly detection can identify abnormal fund outflows, and NLP can capture early signs of bank runs on social platforms, shortening the risk detection window from weeks to days. However, effective technical early warning depends on bank data transparency and regulatory coordination. The article concludes by reminding depositors to diversify savings and recommending that technology professionals build explainable risk models and promote AI risk control alongside RegTech.
Event Overview
According to a discussion on Hacker News, a bank in Paraguay has collapsed, and half of the country's population has their savings tied to this bank. The post received 23 points on Hacker News and sparked 3 comments. Although the original discussion saw limited engagement, the systemic financial risk revealed by the event itself warrants deeper examination.
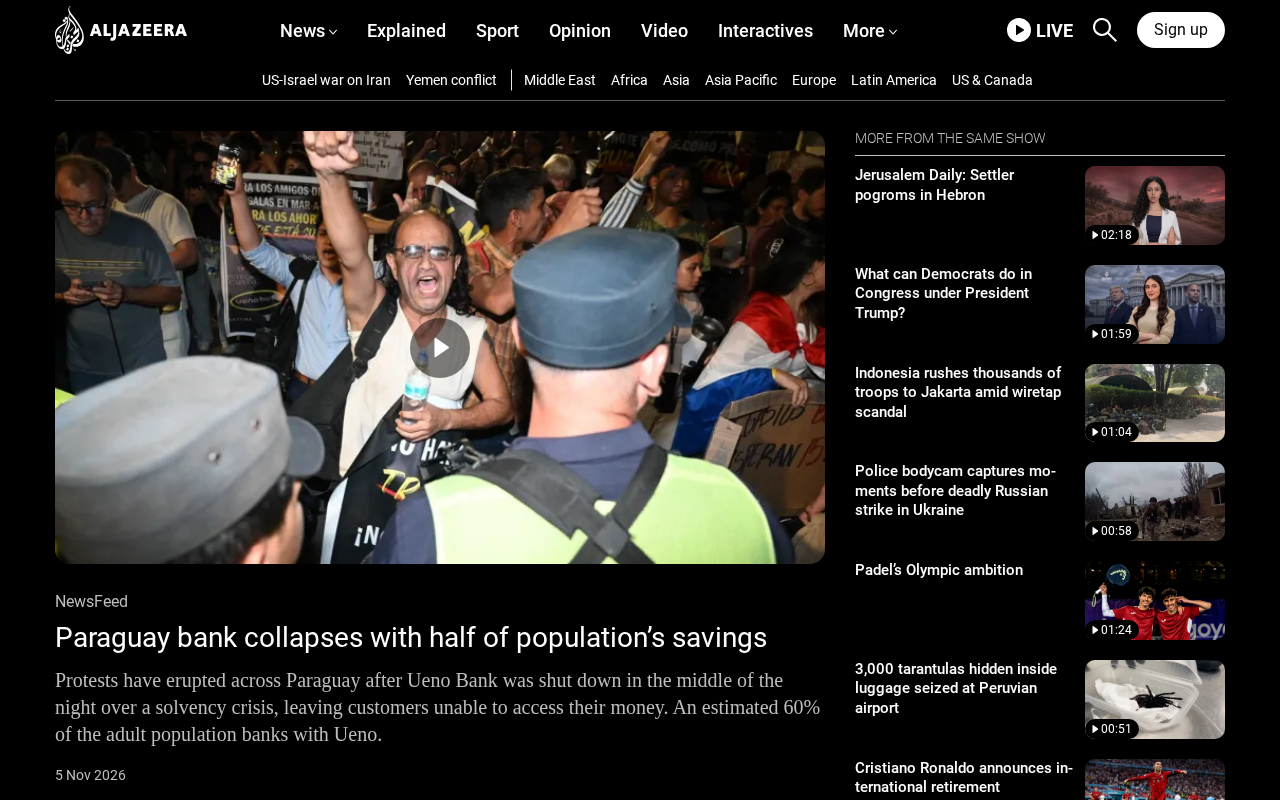
From a technical perspective, events like this are precisely the scenarios where AI can deliver value in financial risk monitoring and early warning. It should be noted, however, that the original source only provides a title and minimal metadata, lacking the specific bank name, collapse details, and official responses. Therefore, the analysis in this article is more of a deduction based on publicly available information frameworks rather than a definitive account of the full picture.
Why "Half the Population's Savings" Is So Devastating
When half a country's population has its savings concentrated in a single bank, this is no longer merely the operational failure of one institution—it represents an amplification of vulnerabilities across the entire financial system. Savings are the fundamental buffer for households to cope with unemployment, illness, and retirement. Once a bank cannot honor withdrawals, consumption and investment contract simultaneously, dragging down the real economy.
The deeper problem lies in trust. The banking system operates on depositors' confidence that they can withdraw their money at any time. Once that confidence collapses, a bank run rapidly depletes liquidity. For countries with smaller economies and limited financial regulatory resources, such shocks often exceed the rescue capacity of the central bank.
Bank Runs and Deposit Insurance Mechanisms
A bank run refers to the behavior of depositors rushing to withdraw their savings out of fear that a bank will fail. Because banks operate on a fractional reserve system—holding only a small amount of cash to meet routine withdrawals—even a fundamentally sound bank can collapse from liquidity depletion once a run occurs. Deposit insurance was designed precisely to break this chain: an insurance institution provides limited coverage for each depositor's savings, thereby reducing the incentive for individual depositors to join a run. However, in economies with insufficient financial depth, the coverage scope and fund size of deposit insurance are often limited. When half the population's savings are concentrated in one bank, the insurance fund may simply be unable to pay out—a textbook manifestation of systemic risk.
Can AI Serve as an "Early Warning System" for Financial Risk
In traditional financial regulation, risk signals often depend on quarterly financial reports and on-site inspections, creating significant time lags. AI models, by contrast, can integrate unstructured data such as transaction flows, social media sentiment, and ATM withdrawal frequency to build more timely risk indicators.
Specifically, anomaly detection-based models can identify patterns such as abnormal fund outflows and concentrated depositor withdrawals; natural language processing can scan news and social platforms to capture early discussions signaling a bank run. These technologies are not a panacea, but they can shorten the window for detecting risk from weeks to days or even hours.
However, the limited discussion in the Hacker News comment section also highlights a reality: the value of technical tools depends on the availability of data and the support of regulatory frameworks. If banks disclose information opaquely and regulators do not share data, even the most advanced models cannot function effectively.
The Role of Anomaly Detection and Natural Language Processing in Financial Risk Control
Anomaly detection is a class of machine learning methods that learn "normal" patterns from historical data and flag samples that significantly deviate from those patterns as anomalies. In bank risk control scenarios, it can be used to identify unusual large transfers, sudden spikes in withdrawal frequency over a short period, and similar behaviors. Natural language processing (NLP) enables models to parse text from news, forums, and social platforms, capturing the spread of panic sentiment through sentiment analysis and topic identification. Combined, the two can form a real-time perception layer for liquidity risk. However, such models are highly dependent on the quality and representativeness of training data; if the data itself is biased or lagging, early warning signals may also be distorted.
Regulatory Technology (RegTech)
Regulatory technology refers to the use of technological means to improve the efficiency and timeliness of financial regulation, covering areas such as automated reporting, real-time transaction monitoring, and compliance risk identification. Unlike AI risk control within institutions, RegTech emphasizes data standardization and sharing mechanisms between regulators and regulated entities. In markets where the digitalization levels of small and medium-sized banks vary widely, the implementation of RegTech often requires regulators to take the lead in establishing data interface standards. Otherwise, AI early warning models can only see fragmented information and struggle to form a complete judgment on systemic risk.
Implications for Ordinary Depositors and Technology Professionals
At the individual level, this event reminds people of the importance of diversifying savings and paying attention to deposit insurance systems. For technology professionals, especially those in fintech and data science, this case illustrates the necessity of building transparent, explainable risk models—models must not only be able to warn but also enable regulators and the public to understand the basis for the warning.
From an industry perspective, small and medium-sized banks in emerging markets often prioritize business expansion over risk infrastructure in their digitalization efforts. The implementation of AI risk control needs to advance in coordination with regulatory technology (RegTech), rather than serving as an isolated marketing selling point.
Conclusion
Public information about the Paraguay bank collapse remains limited, but the systemic risk and the space for technological response that it reveals are clear. AI is not a universal cure for financial risk, but it can become an important tool for regulators and institutions to detect problems earlier. The subsequent developments of this event deserve continued attention.
One-line Summary
A bank collapse in Paraguay involving half the population's savings exposes systemic financial risk and the space for AI early warning.
Paragraph Summary
The article begins with a Hacker News discussion about a bank collapse in Paraguay, noting that half the country's population has savings concentrated in a single bank. If the bank cannot honor withdrawals, it would trigger a chain reaction of bank runs, consumption contraction, and shocks to the real economy. The author argues that such events are precisely where AI can add value in financial risk monitoring: anomaly detection can identify abnormal fund outflows, and natural language processing can capture early signs of bank runs on social platforms, shortening the risk detection window from weeks to days. However, the effectiveness of technical early warning depends on bank data transparency and the support of regulatory frameworks. The article concludes by reminding depositors to diversify savings and pay attention to deposit insurance, and recommending that technology professionals build explainable risk models and promote the coordinated implementation of AI risk control and regulatory technology.
Related articles
 Tech Frontiers
Coldframe: A Honeypot Disguised as a Supermarket Freezer Controller
Coldframe is a honeypot disguised as Danfoss AK-SM 800A and Dixell XWEB freezer controllers, built as a single Python file that detects CVE-2025-41450 attempts and is identified as real devices on Shodan.
 Tech Frontiers
GRFNet: A Lightweight PyTorch Model Designed for Multichannel Time-Series Classification
GRFNet is a lightweight PyTorch model for multichannel time-series classification, originating from EEG decoding research. With only 3,847 parameters, it is based on the ROCKET architecture, combining random convolution kernels with learnable spatial filters, supports arbitrary input lengths, and will soon be evaluated on the PhysioNet dataset.
 Tech Frontiers
CUDA-Accelerated Rocket League Simulator: A Player-Made Hardcore Experiment
A Reddit post shows a "100% Accurate" Rocket League simulator accelerated with CUDA. We analyze its technical context, CUDA's value in game physics simulation, and the significance and limitations of such community projects.