'The Big Short' Investor Eisman on Anthropic IPO: How Will Investors Price the Future of AI?

Using Eisman and an Anthropic IPO as a starting point, this breaks down the key variables and bull-bear debates in AI company pricing.
A Hacker News post juxtaposing 'Big Short' investor Steve Eisman with an Anthropic IPO raises the question of how a frontier AI lab should be priced in public markets. If Anthropic lists, valuation logic would need to shift from PE/PS multiples to revenue structure, customer concentration, inference cost curves, gross margin path, and special governance structure. Bull-bear debate centers on early AI penetration versus whether capex has pulled forward future demand.
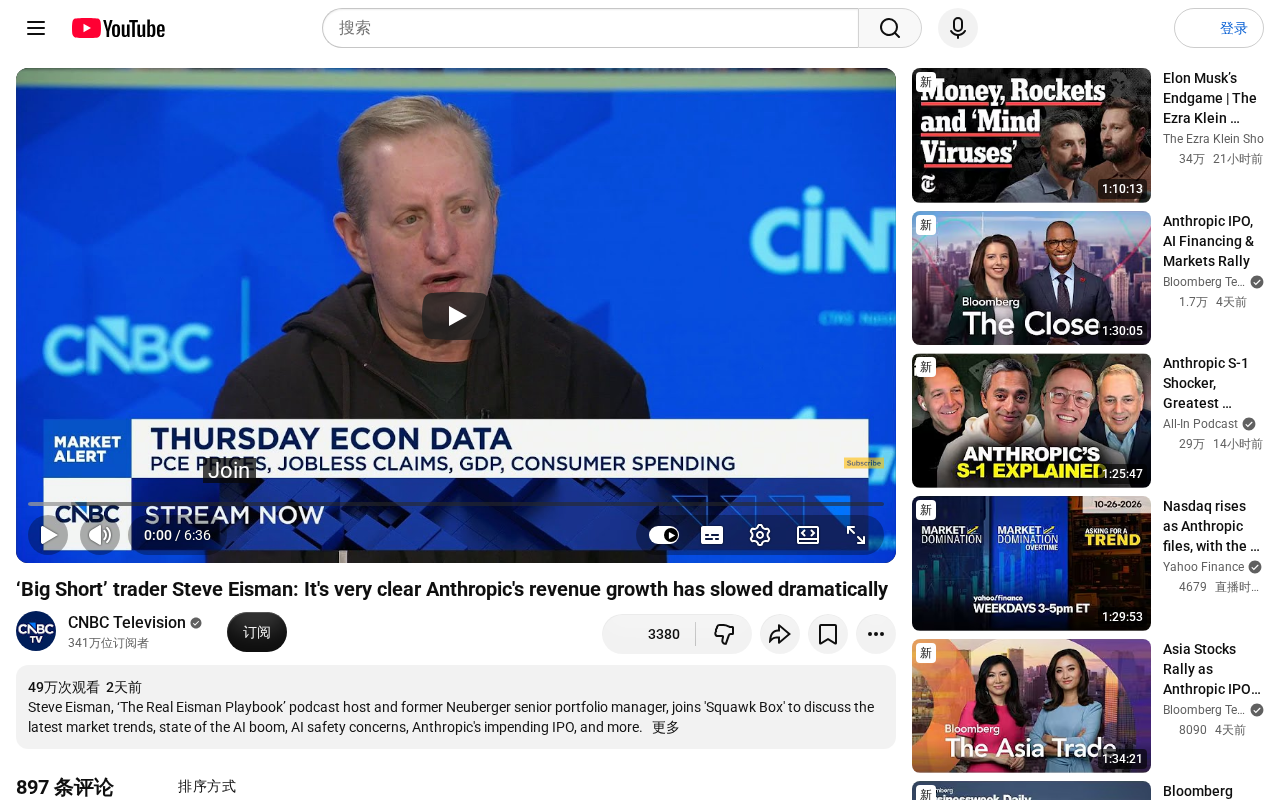
A Hacker News discussion titled "'Big Short' Trader Steve Eisman on Anthropic IPO" puts two seemingly unrelated keywords into the same sentence: investor Steve Eisman, famous for shorting subprime mortgages, and Anthropic, an AI company that has not yet gone public. The post itself contains only a title and a brief discussion, but the question it raises is very specific—when a frontier AI lab heads to the public markets, what framework should investors use to price it?
Background: A Discussion Sparked by a Headline
The information in this Hacker News post is concentrated in the title itself. There are not many comments, but the direction is clear. Eisman is widely known to the public through the book and film The Big Short, and his public statements usually revolve around structural risks in the financial system. Placing an investor known for "identifying bubbles" alongside the topic of an Anthropic IPO naturally centers the discussion on one question: how much of an AI company's valuation reflects real demand, and how much is narrative premium?
It should be noted that this source material provides only a title and minimal metadata—no specific views from Eisman, no Anthropic IPO timetable, and no financial data. The analysis below, based on this topic, is an extended interpretation of the discussion's direction rather than a retelling of the original remarks.
Why an Anthropic IPO Is Being Juxtaposed with "The Big Short"
The Tension Between Narrative-Driven and Fundamentals
Eisman's public image is built on "seeing structural cracks when most people are optimistic." The AI industry's current state happens to have exactly the characteristics he is skilled at examining: enormous capital expenditure, rapid revenue growth but an unclear path to profitability, and top companies' valuations highly dependent on expectations for future compute demand. As one of the frontier model companies, Anthropic's IPO would be seen as a public pricing test for the entire AI asset class—how much premium the market is willing to pay for "intelligence not yet realized."
Public Markets Lack Pure AI Targets
Before Anthropic, most AI exposure available to ordinary investors came from segments of large technology companies or from supply chain companies around compute hardware. The listing of a pure frontier model company means the valuation logic needs to shift from "PE/PS multiples" to an item-by-item breakdown of technology roadmaps, customer contracts, compute cost curves, and regulatory risk. This is also the implicit judgment in the discussion: IPO pricing is not just a financial issue, but a public vote on the pace of AI commercialization.
PS (Price-to-Sales) is a commonly used metric for valuing high-growth, not-yet-profitable companies. It divides market capitalization by trailing twelve-month revenue and reflects the price the market is willing to pay for each unit of revenue. Traditional software companies often have PS in the 5 to 15 range, while frontier AI companies may have PS as high as dozens of times because of extremely fast growth. PE (price-to-earnings) requires a company to already have stable net profit, so it is not yet applicable to most AI labs. When the article says the valuation logic needs to shift from "PE/PS multiples," it means that simply applying multiples is no longer enough to explain pricing; one must break down revenue quality, cost structure, and growth sustainability. Multiples are only the result; assumptions are the cause—and this is also the entry point for Eisman-style scrutiny: what growth and margin assumptions are embedded behind the multiples, and can those assumptions withstand stress testing?
Several Variables Investors May Focus On
Revenue Structure and Customer Concentration
Frontier model companies' revenue often comes from a small number of large enterprise customers and API calls. This structure amplifies volatility after listing: whether a single large customer renews can significantly change revenue expectations. Investors need to distinguish the proportion of "long-term contracts" versus "pay-as-you-go" revenue, as well as the share of inference costs in revenue.
Compute Costs and the Gross Margin Path
Compute spending on training and inference is the largest cost item for such companies. If the IPO filing discloses gross margin trends, the market will focus on whether unit inference costs decline with scale. Eisman-style scrutiny would ask: is current growth built on subsidized pricing, and if prices rise, how elastic is demand?
Inference cost refers to the compute expense consumed when a model responds to user requests (rather than during training), usually measured in dollars per million tokens. For API businesses, inference cost goes directly into cost of revenue and determines gross margin. As model scale and user volume grow, inference costs may rise nonlinearly unless unit costs are optimized through methods such as model distillation, quantization, specialized chips, or batch processing. When the article focuses on "whether unit inference costs decline with scale," the essential question is: does this company have true economies of scale, or does it lose more as it grows? If inference costs decline more slowly than price competition drives prices down, gross margin will be squeezed from both ends, and the faster it grows, the larger the cash flow gap. This is also a key financial clue for distinguishing "subsidies for growth" from a "sustainable business model."
Regulation and Governance Structure
AI labs generally carry the legacy of nonprofit or special governance structures, and Anthropic is no exception. Going public means higher governance transparency requirements, and the tension between safety commitments and shareholder returns will become an unavoidable chapter in the prospectus.
Anthropic uses a Public Benefit Corporation (PBC) structure and has established a Long-Term Benefit Trust in its governance. The trust appoints some board members to ensure that the safety mission is not diluted under shareholder pressure. A PBC is a U.S. legal entity form that requires a company to pursue shareholder returns while also considering the public mission stated in its charter; directors must balance both in decision-making rather than being accountable only to shareholders. This structure will create unique governance issues after listing: public market investors usually demand ultimate control through one person, one vote or one share, one vote, while safety-oriented trust arrangements may be seen as weakening shareholder influence. The prospectus will need to clearly disclose the boundaries of the trust's authority, scenarios of conflict with ordinary shareholders' interests, and the threshold for changing mission provisions. Whether this results in a governance discount or a governance premium will become part of the pricing discussion.
Possible Points of Divergence Between Bulls and Bears
Bulls will emphasize that AI penetration is still at an early stage, that top model companies' revenue growth far exceeds that of traditional software companies, and that public markets should assign a growth premium; that compute costs will decline over the long term, and economies of scale will gradually emerge.
Bears will borrow Eisman's framework and ask in return: has current capital expenditure already pulled forward several years of future demand; is the capability gap between models narrowing, leading to price wars; and most importantly—if AI monetization is slower than the pace of infrastructure investment, who bears the cash flow gap in between?
These two views are not elaborated in the brief Hacker News discussion, but they constitute the real analytical value of the Anthropic IPO topic: not predicting the first-day move, but clarifying the assumptions behind AI asset pricing.
What It Means for Ordinary Observers
Even though details of an Anthropic IPO have not yet been made public, the topic is still worth following. It provides an observation window: when a "Big Short"-style skeptical lens meets the AI narrative, how will the public market's pricing mechanism respond? For practitioners, this means the financing environment, valuation benchmarks, and talent flows may all change accordingly; for investors, it is an opportunity to learn how to break down the fundamentals of AI companies.
The original material contains limited information, and Eisman's specific arguments cannot be reconstructed here. But the combination of "Eisman + Anthropic IPO" itself already shows that the AI industry is moving from the narrative stage of private markets to a stage where it must undergo item-by-item scrutiny by public markets.
One-line Summary
Using the juxtaposition of "Big Short" investor Eisman and an Anthropic IPO as a starting point, this breaks down the key variables and bull-bear disagreements in the public pricing of AI companies.
Paragraph Summary
A Hacker News post juxtaposing "Big Short" investor Steve Eisman with an Anthropic IPO raises the question of how a frontier AI lab should be priced when it enters public markets. The article notes that Eisman is known for identifying structural bubbles, and the AI industry's characteristics—high capital expenditure, an unclear path to profitability, and valuations dependent on future compute expectations—are exactly the object of such scrutiny. If Anthropic lists, it would become a rare pure frontier-model target in public markets, and valuation logic would need to shift from PE/PS multiples to an item-by-item breakdown of revenue structure, customer concentration, inference cost curves, gross margin path, and special governance structure. Bull-bear disagreement centers on the early-stage dividend of AI penetration versus whether capital expenditure has pulled forward future demand. The original material contains only a title; this article is an extended analysis of the topic's direction.
Related articles

Anthropic Fable 5.2 Hands-On: 3A Games and Excel Clones from One Prompt
Anthropic Fable 5.2 hands-on: three-line prompts generate a playable Gears of War clone, a full Excel clone, and a DaVinci Resolve clone. Benchmarks, Ultra Code mode, token costs, and pricing analyzed — is it worth replacing Opus 5.5?

RL Racing Agent Stuck Against the Wall? Try These Recovery Strategies
RL racing agent stuck against walls? We analyze recovery data, observation limits, and action space, comparing DAgger, behavior cloning, and SAC with diagnostic experiments.

Giving AI Agents Long-Term Memory: A New Approach to Supply Chain Disruption Decisions
A developer uses Hindsight to build persistent memory for a supply chain AI agent, enabling retrieval of past disruptions and decision outcomes. The article analyzes its architecture, memory retention and recall design, and engineering challenges such as what to remember and how to evaluate memory effectiveness.