Europe's Top 65 Robotics Companies: AI Is Closing Robotics' Biggest Gap

Europe's Top 65 Robotics list shows startups shifting from selling hardware to outcomes, from replacing humans to augmenting them, with AI closing the flexibility gap.
The Venturist's Europe's Robotics 65 list reveals structural changes in European robotics entrepreneurship. Industry and logistics remain the main battleground, but more companies are retrofitting installed equipment — a brownfield robotics strategy — to lower customer decision thresholds. Capital is betting bigger, with several young companies raising nine-figure rounds, and business models shifting from hardware sales to outcome-based billing. AI's intelligence layer is closing robotics' historical weakness — flexibility — pushing robots from specialized equipment toward general-purpose tools. General-purpose robots are an emerging trend, with 42% of post-2021 companies in this category, though commercialization remains highly vertical. University clusters are core nodes of European robotics entrepreneurship, and the consumer market is temporarily absent. Overall: a pragmatic evolution prioritizing retrofit, outcomes, vertical deployment, and augmenting humans.
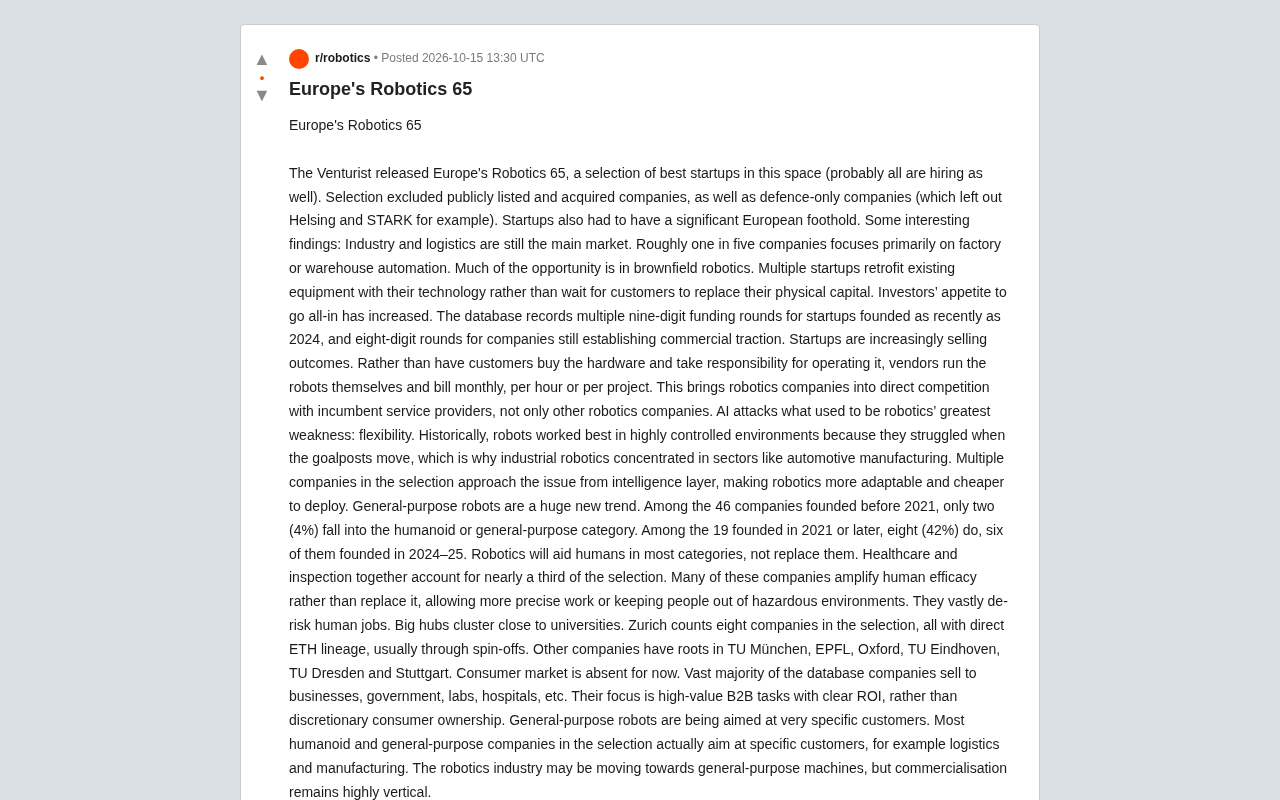
According to the Europe's Robotics 65 list published by The Venturist, Europe's robotics sector is undergoing a structural shift. The list excludes already-public and acquired companies, as well as pure defense players (such as Helsing and STARK), and requires that selected companies have a significant European business footprint. The 65 European robotics startups that made the final cut paint a remarkably clear picture of the industry.
Industry and Logistics Remain the Main Battleground, but the Playbook Has Changed
In terms of market distribution, industry and logistics are still the most concentrated areas for robotics startups. Roughly one in five companies focuses on factory or warehouse automation. But the list reveals an easily overlooked trend: a large share of the opportunity lies not in getting customers to replace their existing equipment, but in retrofitting the installed base.
Several selected companies choose to technically "retrofit" existing equipment — adding sensors, vision systems, or intelligent control layers — rather than waiting for customers to retire old physical capital. This "brownfield robotics" strategy dramatically lowers deployment costs and the customer's decision threshold, and makes it easier for startups to gain entry when customer budgets are tightening.
Brownfield robotics borrows the concept from the industrial distinction between "brownfield" and "greenfield." A greenfield project means building an entire new set of facilities and processes from scratch on empty land; brownfield means retrofitting and upgrading on top of existing equipment, production lines, and information infrastructure. In the robotics industry, a brownfield strategy means companies don't ask customers to scrap their expensive existing physical capital (such as forklifts, robotic arms, or conveyor lines), but instead add sensors, vision modules, or intelligent control layers to give old equipment new automation capabilities. The economic logic: customers avoid the capital expenditure and production-halt risk of replacing an entire line, the decision chain is shorter, and deployment timelines compress from months to weeks. For manufacturing and logistics customers with tight budgets or extreme sensitivity to downtime, this path faces far less resistance than selling brand-new equipment.
Investors Are Betting Bigger
The list's database contains multiple nine-figure funding rounds, and some of these companies aren't very old. In one telling detail, some companies still building commercial traction have also raised eight-figure rounds.
This signals that capital markets' willingness to go "all in" on robotics is rising. Investors are no longer waiting only for revenue validation before acting — they're willing to bet on teams and technology roadmaps at earlier stages. For founders, this is both a window of opportunity and a sign that the competitive pace will only quicken.
A nine-figure funding round typically means $100 million or more, a rare magnitude in the early-stage startup context. Such rounds are often led by large growth funds or corporate capital, usually corresponding to higher valuations and greater expectations for subsequent growth. An eight-figure round refers to the $10 million to $99.99 million range, more common at Series A and B stages. It's worth noting that robotics startups differ from general software startups: they simultaneously involve hardware, supply chains, mass production, and on-site deployment, burn cash faster, and have longer validation cycles. So when capital is willing to commit large sums before revenue has been validated at scale, it means investors are actually betting on the team's technological moat and the sector's long-term structural opportunity — not short-term financial metrics. This judgment also means that once startups secure large sums, they must accelerate product deployment and scenario replication, or valuation pressure on subsequent rounds will rise significantly.
From Selling Hardware to Selling Outcomes: The Business Model Is Shifting
One notable change is that robotics companies are increasingly "selling outcomes" rather than "selling equipment."
In the traditional model, customers buy hardware and bear operational responsibility themselves. Now, many vendors choose to operate the robots themselves, billing customers monthly, hourly, or per project. This model pushes robotics companies directly into competition with existing service providers — their rivals are no longer just other robotics companies, but all businesses offering similar services.
This shift places higher demands on startups' operational capabilities, but once it works, customer stickiness and revenue predictability are clearly superior to simply selling hardware.
AI Is Closing Robotics' Biggest Historical Gap
What has long been robotics' greatest weakness? Flexibility.
In the past, robots excelled in highly controlled environments — which is why industrial robots long concentrated in scenarios like automotive manufacturing. Once the target or environment changes, traditional robots struggle to adapt. And AI, especially the introduction of the intelligence layer, is directly attacking this weakness.
Several companies on the list enter through the intelligence layer, making robots more adaptable to change with lower deployment costs. This is precisely the key step in robotics' evolution from "specialized equipment" to "general-purpose tool."
General-Purpose Robots: A New Trend, but Commercialization Remains Vertical
General-purpose robots are the most striking new trend on the list. Among the 46 companies founded before 2021, only two (4%) fall into the humanoid or general-purpose robot category. Among the 19 companies founded in 2021 or later, eight (42%) belong to this category, six of which were founded in 2024-2025.
But here's an easily misread point: most general-purpose robotics companies are actually targeting very specific customers. Logistics and manufacturing are the most common target scenarios. The industry may be evolving toward general-purpose machines, but commercialization remains highly vertical.
The intelligence layer refers to the upper software portion of a robotic system responsible for perception, understanding, decision-making, and task planning, as distinct from the low-level motion control and hardware body that executes specific actions. The reason traditional industrial robots can only work in highly controlled scenarios like welding and painting is precisely the lack of this layer's ability to understand environmental change — when positions shift, object poses change, or new tasks appear, the system cannot respond autonomously. In recent years, intelligence layers based on deep learning and reinforcement learning have begun handling object recognition, grasping planning, natural language instruction understanding, and even cross-task transfer, enabling the same hardware to adapt to new scenarios through software updates. This is also the technical precondition for "moving from specialized equipment to general-purpose tools": generality doesn't come from changes in mechanical structure, but from improvements in the intelligence layer's generalization capability.
Robots Augment Humans, Not Replace Them
Healthcare and inspection companies together account for nearly one-third of the list. Most of these companies are augmenting human efficiency rather than replacing humans — making work more precise or removing people from hazardous environments.
The data suggests robots are more likely to "de-risk" human jobs than eliminate them. This conclusion is exactly the opposite of many public narratives.
Universities Are the Core Nodes of European Robotics Entrepreneurship
There's another geographic feature worth noting: major startup clusters are almost all adjacent to universities. Zurich has eight companies selected, all with direct ties to ETH, usually founded through spin-offs. Others originate from TU Munich, EPFL, Oxford, Eindhoven University of Technology, TU Dresden, and the University of Stuttgart.
This explains why European robotics entrepreneurship isn't evenly distributed — it depends heavily on academic institutions' research spillover and talent supply.
Spin-off refers to a commercial entity established by a team at a university, research institution, or large corporation that independently commercializes its research results or technology assets. In the European robotics field, this model is especially common: labs at ETH, TU Munich, and other universities have long accumulated core research in robot control, machine vision, and motion planning, and when results approach usability, doctoral students or researchers use a spin-off to transform prototypes from papers into sellable products. This approach preserves the research institution's continuous talent supply while giving startups a high technological starting point from the outset. It also explains the geographic concentration of European robotics clusters — startups don't distribute evenly, but cluster tightly around universities with strong engineering departments and mature technology transfer mechanisms, forming a talent-and-capital cycle similar to that between Silicon Valley and Stanford.
The Consumer Market Is Temporarily Absent
The vast majority of companies on the list sell to enterprises, governments, labs, and hospitals. Their focus is high-value B2B tasks with clear ROI, not consumer products that individual buyers decide to purchase. The consumer robotics market is essentially absent from this list.
This isn't hard to understand: B2B scenarios have clear demand and strong willingness to pay, while consumer robots face more demanding requirements on price and experience, and current technology maturity can't yet support a commercial闭环 for large-scale consumer products.
What This List Tells Us
Europe's Robotics 65 presents not a narrative of "robots about to replace humans," but a more pragmatic industry evolution: retrofitting the installed base takes priority over equipment replacement, selling outcomes takes priority over selling hardware, vertical deployment takes priority over general-purpose visions, and augmenting humans takes priority over replacing them. AI's arrival is solving robotics' most fundamental flexibility challenge, but the path to commercialization remains specific, scenario-driven, and predominantly B2B.
One-line Summary
Europe's Top 65 Robotics list shows robotics startups shifting from selling hardware to selling outcomes, from replacing humans to augmenting them, with AI closing the flexibility gap.
Paragraph Summary
The Venturist's Europe's Robotics 65 list reveals structural changes in European robotics entrepreneurship. Industry and logistics remain the main battleground, but more companies are choosing to retrofit installed equipment — a brownfield robotics strategy that lowers customer decision thresholds. Capital is betting bigger, with several young companies raising nine-figure rounds, and business models shifting from selling hardware to outcome-based billing. AI's intelligence layer is closing robotics' historical weakness — flexibility — driving robots from specialized equipment toward general-purpose tools. General-purpose robots are an emerging trend, with 42% of post-2021 companies in this category, though commercialization remains highly vertical. University clusters are the core nodes of European robotics entrepreneurship, and the consumer market is temporarily absent. Overall, the picture is one of pragmatic evolution: retrofit first, outcomes first, vertical deployment first, augment humans first.
Related articles

"Black October": Did AI Uncover 3% of All Critical Vulnerabilities Ever?
A Reddit post claims 3% of all critical software vulnerabilities ever were found in the past month, dubbed 'Black October.' We break down the statistical issues, how AI-assisted code auditing accelerates discovery, and how developers should respond.

Microsoft Project Gecko: Using AI to Bridge Language Gaps for African Farmers
Microsoft's Project Gecko launches PharmaChat, letting African farmers ask questions in their native language and get precise video clips and farming book chapters via AI. The project also releases three interactive manuals to advance inclusive AI.

Musk's Space Dominance: How Starlink Throttling Undermines Ukraine's Defense
SpaceX's Starshield throttling disabled Ukraine's high-speed interceptor drones, exposing how Musk's private control over low Earth orbit communications affects battlefield dynamics and national security, and highlighting the risks of commercial space militarization and space governance dilemmas.