MSAR: Modular Multi-Scale Autoregression Revolutionizes Time Series Forecasting
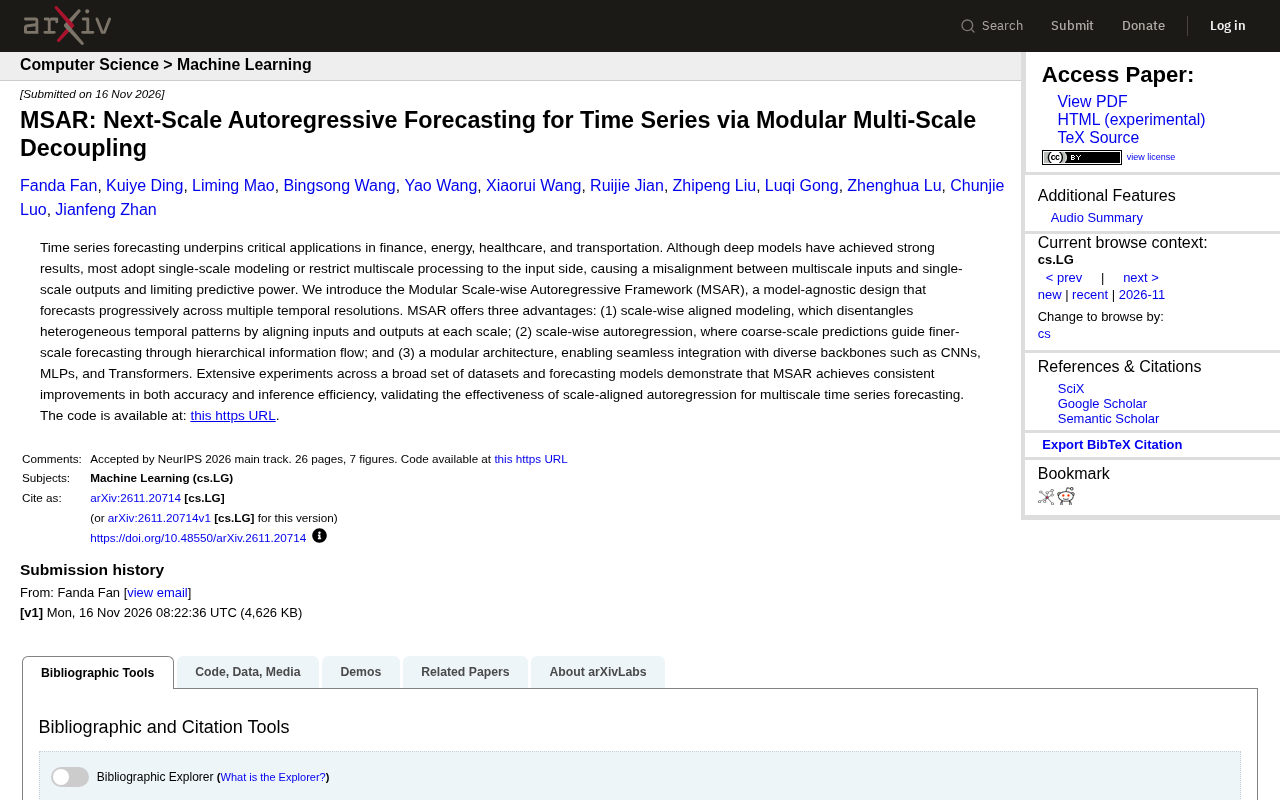
MSAR enables progressive multi-scale time series forecasting via scale alignment and scale autoregression, with a modular design compatible with various backbones.
The article introduces MSAR, a modular scale autoregressive framework that addresses the misalignment between multi-scale inputs and single-scale outputs in time series forecasting. MSAR aligns inputs and outputs at each temporal resolution and achieves progressive forecasting through hierarchical information flow from coarse to fine scales. It is model-agnostic and integrates seamlessly with CNN, MLP, and Transformer backbones. Experiments show consistent improvements in accuracy and inference efficiency, and the code is open-sourced on GitHub. The article also discusses implications for multi-scale modeling and future directions including backbone integration and scale drift in non-stationary series.
Time series forecasting is a key supporting technology across fields such as finance, energy, healthcare, and transportation. Although deep learning models have achieved remarkable results, most methods adopt single-scale modeling or restrict multi-scale processing to the input side, resulting in a misalignment between multi-scale inputs and single-scale outputs that limits forecasting capability. The recently proposed Modular Scale Autoregressive framework (MSAR) offers a new approach to this problem by progressively forecasting across multiple temporal resolutions.
The Misalignment Problem in Multi-Scale Time Series Forecasting
Traditional time series forecasting models typically face a fundamental contradiction: real-world time series often contain patterns at different temporal scales (such as short-term fluctuations and long-term trends), yet models either focus on a single scale or perform multi-scale feature extraction only at the input side while the output remains single-scale. This scale misalignment between input and output makes it difficult for models to fully exploit multi-scale information, limiting forecasting accuracy.
MSAR was proposed precisely to resolve this misalignment. The core idea of the framework is to align inputs and outputs at each scale and to achieve progressive forecasting through autoregressive information flow across scales.
Autoregressive models are a class of statistical models that use their own historical observations as input to predict future values; the classic form, AR(p), predicts the next time step through a linear combination of the preceding p time steps. In deep learning, autoregression extends to the paradigm of generating sequences step by step along the time axis, with typical representatives including the causal attention mechanism of Transformer decoders and the dilated convolution structure of WaveNet. Traditional temporal autoregression unfolds along the time axis, with each step depending on the output of the previous step; the scale autoregression proposed by MSAR, by contrast, switches the unfolding dimension from time steps to temporal resolutions, where coarse-scale predictions serve as conditional inputs to guide fine-scale generation. The two differ fundamentally in the direction of information flow and dependency structure. Understanding this distinction helps grasp the innovative positioning of MSAR in multi-scale modeling.
Three Core Advantages of MSAR
MSAR is a model-agnostic design with three notable characteristics:
Scale-aligned modeling: By aligning inputs and outputs at each scale, MSAR can decouple heterogeneous temporal patterns, enabling the model to learn regularities separately at different resolutions and avoid scale confusion.
Scale autoregression: Coarse-scale predictions guide fine-scale predictions through hierarchical information flow, forming a progressive coarse-to-fine forecasting process. This autoregressive mechanism differs from traditional time-step autoregression in that it unfolds along the scale dimension, better matching the hierarchical structure of multi-scale time series.
Modular architecture: MSAR's design allows seamless integration with a variety of backbone networks, including CNN, MLP, and Transformer. This means researchers and developers can embed MSAR modules to enhance multi-scale forecasting capability without changing the main structure of existing models.
Backbone network refers to the main neural network structure responsible for the primary feature extraction and representation learning tasks, whose output is typically fed into a task-specific head to produce the final prediction. In the time series domain, common backbones include temporal convolutional networks (TCN) for capturing local patterns, Transformer variants adept at modeling global dependencies (such as PatchTST and iTransformer), and lightweight, efficient MLP structures (such as DLinear). MSAR's modular design means that its scale alignment and autoregressive logic are independent of the specific backbone implementation; the backbone is only responsible for feature transformation within a single scale, while information scheduling across scales is managed uniformly by the MSAR framework. This decoupling allows researchers to inject multi-scale capability into any existing architecture without redesigning the network body, and also provides controlled experimental conditions for horizontally comparing the performance of different backbones under a unified multi-scale paradigm.
Experimental Validation and Performance
The authors conducted experiments on a wide range of datasets and forecasting models, and the results show that MSAR achieves consistent improvements in both accuracy and inference efficiency. This validates the effectiveness of scale-aligned autoregression in multi-scale time series forecasting. You may not have noticed that, as a model-agnostic framework, MSAR's performance gains can be reproduced across different backbones, which provides flexibility for its practical application.
Implications for the Time Series Forecasting Field
MSAR's proposal reflects the ongoing exploration of multi-scale modeling in the time series forecasting field. Previous multi-scale methods mostly focused on input-side feature engineering or network design, whereas MSAR carries the multi-scale idea through to the output side and the forecasting process itself, forming a closed loop. This scale autoregression approach resembles multi-scale prediction in computer vision and hierarchical generation in natural language processing, and may inspire further cross-domain architectural innovation.
In addition, MSAR's modular nature lowers the barrier to technical adoption. Developers can use it as a plug-in component to quickly integrate into existing forecasting pipelines, making it especially suitable for scenarios requiring handling of multi-scale periodicity, such as energy load forecasting and financial asset price prediction.
Non-stationary time series refers to series whose statistical properties (such as mean, variance, and autocorrelation structure) change over time; financial prices, sensor readings, and traffic flows all fall into this category. The core challenge posed by non-stationarity is that the pattern distribution learned during training may shift relative to the inference stage, i.e., distribution drift. Under a multi-scale framework, this problem manifests as scale drift: the period lengths or trend slopes at different temporal resolutions may change with the environment, causing the information passed from coarse-scale predictions to fine scales to become biased or even misleading. Common countermeasures include instance normalization (RevIN), distribution adaptation layers, and online update mechanisms, but how to dynamically correct drift within the information flow of scale autoregression remains a key problem that MSAR-type frameworks must solve before practical deployment.
Open Source and Reproducibility
MSAR's code has been open-sourced on GitHub (https://github.com/Oryxo/MSAR), facilitating reproduction and extension by the research community. The open-source initiative helps accelerate the framework's adaptation and optimization across different domains, and also provides a benchmark for subsequent research.
As the scale of time series data grows and application scenarios become more complex, the importance of multi-scale modeling is increasingly prominent. Through scale alignment and autoregressive mechanisms, MSAR provides a concise and effective paradigm for multi-scale forecasting, and its modular design paves the way for industrial deployment. In the future, how to combine MSAR with more advanced backbones and how to handle scale drift in non-stationary time series are worthy of further exploration.
One-line Summary
MSAR achieves progressive multi-scale time series forecasting through scale alignment and scale autoregression, with a modular design compatible with various backbones.
Paragraph Summary
The article introduces a modular scale autoregressive framework called MSAR, aimed at solving the misalignment problem in multi-scale time series forecasting where inputs are multi-scale but outputs are single-scale. The core idea of MSAR is to align inputs and outputs at each temporal resolution and to achieve progressive forecasting through hierarchical information flow in which coarse-scale predictions guide fine-scale predictions. The framework is model-agnostic and can be seamlessly integrated with backbones such as CNN, MLP, and Transformer. Experiments show that MSAR achieves consistent improvements in both accuracy and inference efficiency, and the code has been open-sourced on GitHub. The article also discusses MSAR's implications for closing the loop in multi-scale modeling, as well as future research directions in backbone integration and scale drift in non-stationary series.
Related articles
Gemini 4 Neon Hands-On: Can It Challenge Opus 5.5?
Google released 4 Gemini 4 models in 49 days. We test whether Neon can challenge Opus 5.5 across benchmarks, real video tasks, and subscription costs.
Former Inmate Reveals Psychopath Ratio in Prison: About 200 Out of Every 880
Former inmate Larry Lawton shares on Lex Fridman's podcast that about 200 of 880 life-sentence inmates are psychopaths—a 23% ratio. He explores the blurred line between good and evil, social dynamics in prison, and wisdom from dark experiences.

Getting Started with Local AI: A Practical Guide to Inkling, Qwen, and Unsloth
A beginner's guide to local AI, explaining the roles of Inkling, Qwen, and Unsloth in local LLM deployment and fine-tuning, covering model selection, quantized inference, lightweight fine-tuning workflows, and trade-offs between local and cloud solutions.