Nvidia's Next Crossroads: Defend the Fortress or Take a Risk?

Nvidia earns $8,300 per second; after the founder's departure, its strategy will focus mainly on stability.
Using Nvidia's astonishing profit of $8,300 per second as its entry point, the article notes that the company has just lost its visionary founder-CEO, leaving management in transition. The rational choice for the new management is to maintain the existing profit model and avoid aggressive changes that could disrupt cash flow. Aggressive pricing adjustments, disruptive restructuring of core product lines, and large-scale entry into low-margin areas may all be put on hold. For the industry, the leader's stability-first approach gives competitors a window to catch up, but only if the new management preserves profits without losing technological judgment.
The Hidden Worry Behind Earning $8,300 Per Second
According to the original report, Nvidia currently generates net profit of up to $8,300 per second, which means that by the time you finish reading the previous paragraph, the company has already added tens of thousands of dollars to its books. This money-printing level of profitability makes Nvidia one of the most enviable giants in the tech industry. However, the report also points to a key turning point: the company has just lost its visionary founder-CEO due to a series of events. This change casts uncertainty over Nvidia's future.
When a company creates profits at such an astonishing rate, the most rational strategy is often—do not easily rock this profit juggernaut. The original title gives a blunt judgment: Nvidia's next moves will revolve around "anything that will not shake this incredible profit model."
The figure of $8,300 in net profit per second translates to annualized profit on the order of about $260 billion, which is extremely rare in the history of the semiconductor industry. Behind it is Nvidia's near-monopoly share in the data center GPU market and the high switching-cost moat built by its CUDA software ecosystem. The key to understanding this profit structure is that Nvidia's profits do not come from the high gross margin of chip hardware itself, but from its ability to price a combination of "GPU + networking interconnect + system-level solutions + software stack." This also explains why the article repeatedly emphasizes "do not shake the profit model"—once this combination is broken apart, the premium space per unit of computing power will quickly narrow.
Strategic Inertia After the Founder's Departure
The departure of a founder usually means some kind of rupture in a company's DNA, but for a company like Nvidia that has already built a powerful ecosystem and profit machine, strategic inertia in the short term may be more important than transformation. The report suggests that the company's current top priority is to maintain its existing profit rhythm rather than pursue aggressive transformation that could disrupt cash flow.
This "defend the fortress" logic is not unreasonable: profit of $8,300 per second means the cost of any strategic mistake is magnified indefinitely. Without the founder's prestige, the new management is more inclined to prove itself through steady financial performance.
In the context of corporate management, "strategic inertia" usually refers to an organization's ability to perpetuate itself under established resource allocation, supply chain relationships, and customer expectations. For Nvidia, this inertia is reflected in multi-year product roadmap commitments, capacity lock-ins with foundry partners such as TSMC, and developers' long-term dependence on CUDA versions. A founder's personal judgment is often reflected in early bets on technology inflection points, while inertia ensures that daily operations do not lose speed because of personnel changes. The difference between the two is that inertia can maintain the status quo, but it is difficult to make decisive trade-offs when technology routes shift—and this is precisely the core test facing the new management.
Which Directions May Be Touched, and Which Will Not
The original article does not lay out a specific product roadmap, but its core argument allows one to infer the decision-making framework: any move that could threaten the existing high-profit business—such as aggressive pricing strategy adjustments, disruptive restructuring of core product lines, or large-scale entry into low-margin areas—may be put on hold for the time being.
By contrast, areas that can extend advantages without interfering with the main business are more likely to receive resource倾斜. The report's wording suggests that Nvidia's next step will not be to "reinvent itself," but to seek incremental growth on its existing track.
What It Means for the Industry
For practitioners focused on the AI chip supply chain, Nvidia's "stability-first" signal is worth noting. When the industry leader chooses not to disrupt the existing landscape, competitors gain a window of time to catch up, while downstream customers may face a relatively stable pace of product iteration. However, all of this depends on one premise: whether the management after the founder's departure can maintain profits without losing its technological judgment.
The report's conclusion carries a note of warning—when a ship is sailing fast and steady, the greatest danger is instead that the new captain, eager to prove himself, yanks the wheel hard. What Nvidia needs to do next is precisely to restrain that impulse.
One-line Summary
Nvidia earns $8,300 per second, and after the founder's departure its strategy will focus mainly on stability.
Paragraph Summary
Using Nvidia's astonishing profit of $8,300 per second as its entry point, the article points out that the company has just lost its visionary founder-CEO and that management has entered a transition period. Against this backdrop, the rational choice for the new management is to maintain the existing profit model and avoid any aggressive changes that could disrupt cash flow. The article argues that moves such as aggressive pricing adjustments, disruptive restructuring of core product lines, and large-scale entry into low-margin areas may all be put on hold, with resources more likely to flow toward extending advantages without interfering with the main business. For the industry, the leader's stability-first approach means competitors gain a window to catch up and downstream customers face a relatively stable iteration rhythm—but only on the premise that the new management preserves profits without losing technological judgment.
Related articles
US SEC Investigates Nvidia: Possible A…
US SEC Investigates Nvidia: Possible Accounting Issues
The US SEC's investigation into Nvidia focuses on potential accounting issues, not products. The news sparked heated discussion on Hacker News, with the market watching the AI chip giant's financial disclosure quality and regulatory signals.

FBI Crime Database Reportedly Hit by Hackers; Trump Says 'Not Good'
FBI's NCIC reportedly hit by hackers; FBI has launched an investigation and Trump said it's 'not good.' This article covers the incident, NCIC's importance, and law enforcement data security challenges.
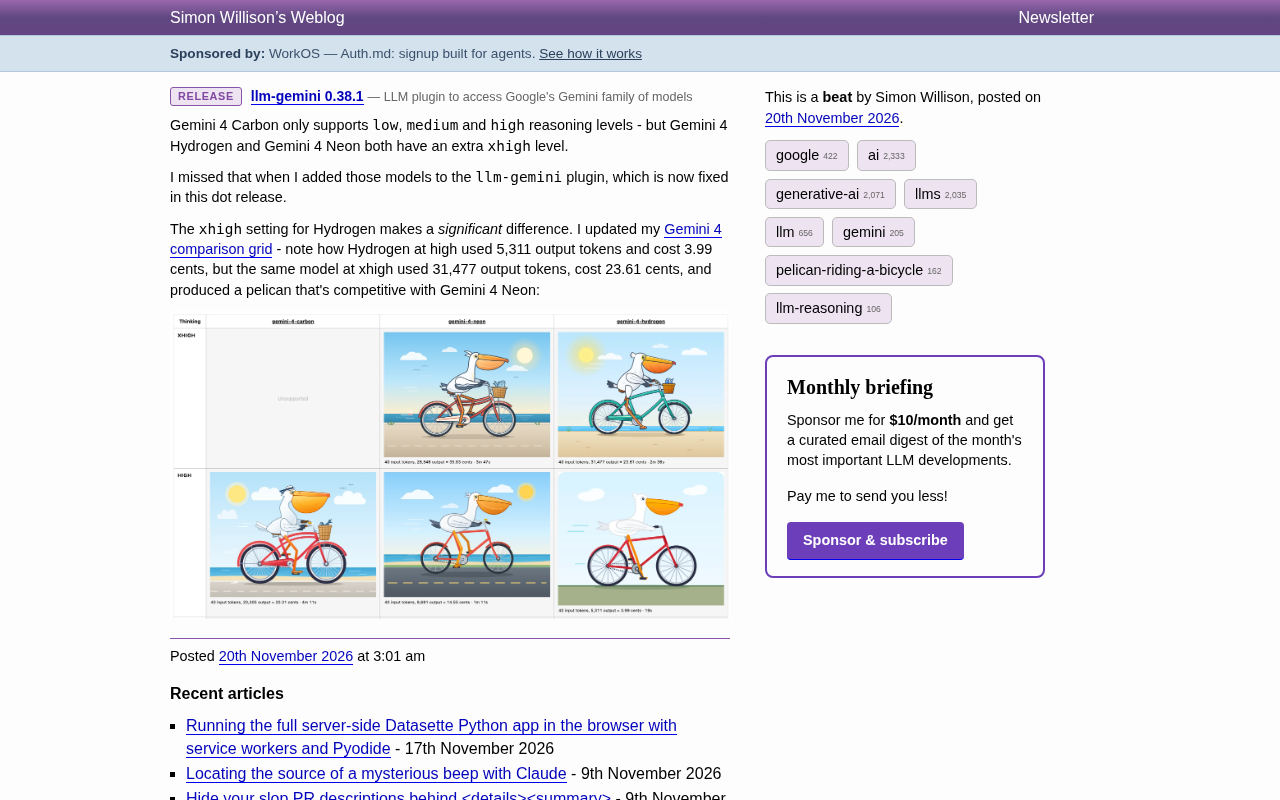
llm-gemini 0.38.1 Fix: Gemini 4 Hydrogen and Neon Gain xhigh Reasoning Level
llm-gemini 0.38.1 fixes the missing xhigh reasoning level for Gemini 4 Hydrogen and Neon. Comparison data shows xhigh sharply raises Hydrogen's output tokens and cost while clearly improving image quality to a level competitive with Neon.