Super-Hot Rock Geothermal: A New Solution to Data Centers' Energy Woes

Geothermal startups bet on super-hot rock to target terawatt-scale baseload power for data centers, but deployment remains unproven.
AI compute expansion is driving up data center electricity demand while grid expansion lags, leading geothermal startups to bet on super-hot rock geothermal: drilling deep into high-temperature hot dry rock to bypass traditional geothermal's geological constraints and generate power almost anywhere. They claim terawatt-scale baseload delivery rather than small demonstrations. Data centers' stable loads and grid-constrained siting make them natural matches for nearby geothermal, and tech companies' willingness to pay for 24/7 clean power makes them ideal anchor customers. But scaling from single-well validation to terawatts involves multiple orders of magnitude of engineering, with high-temperature drilling, reservoir connectivity, and regulatory approvals as key bottlenecks. A cost breakthrough would change data center siting logic, but with no deployed capacity validated yet, focus should be on single-well output and drilling cost curves rather than capacity claims.
Data Centers Are Short on Power, and Geothermal Startups Have Their Sights on "Super-Hot Rock"
The expansion of AI compute has pushed data center electricity demand to unprecedented heights, while grid capacity expansion lags far behind. Against this backdrop, a group of new geothermal startups is betting on a more aggressive technological approach: super-hot rock geothermal. Their judgment is that as long as you drill deep enough and hot enough, you can extract substantial power almost anywhere, thereby bypassing traditional geothermal's dependence on specific geological conditions.
According to RSS source reports, these new players are not aiming for small-scale demonstrations but hope to "leapfrog" current industry leaders and directly deliver terawatts of power. This scale means they are challenging not a niche market but the entire baseload power supply landscape.
The Bottlenecks of Traditional Geothermal and How Super-Hot Rock Differs
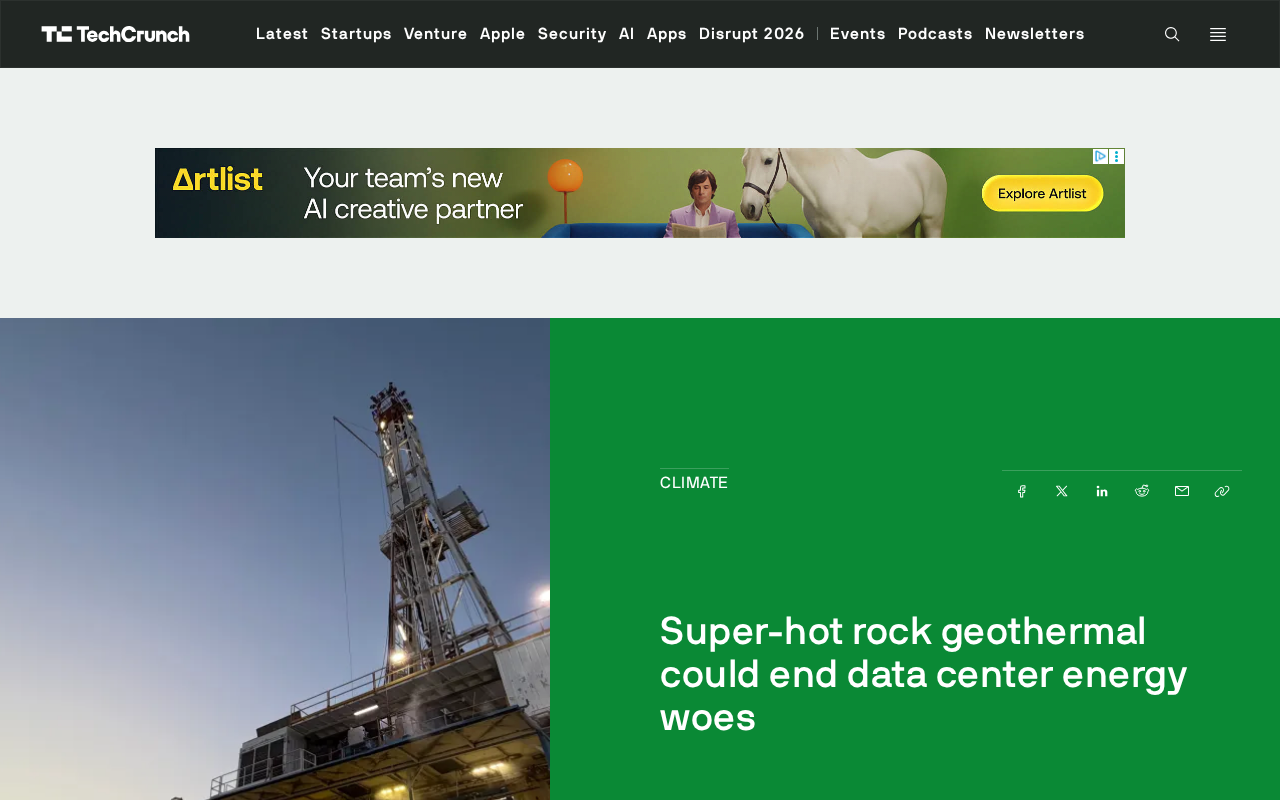
Traditional geothermal power plants rely on naturally occurring high-temperature, high-permeability rock formations, typically concentrated in volcanic belts or plate boundaries, with limited siting options. The super-hot rock approach attempts to drill deep into extremely high-temperature hot dry rock formations, then bring heat to the surface for power generation through engineered reservoirs or closed-loop circulation.
The key variables here are drilling depth and rock temperature. The higher the temperature, the greater the enthalpy per unit of fluid, and the more power can be generated from the same wellhead flow rate; drilling costs, in turn, determine whether a project is commercially viable. The reason this new batch of startups dares to claim "almost anywhere" is precisely the premise that advances in drilling technology have lowered the cost of deep wells.
Hot Dry Rock and Enhanced Geothermal Systems (EGS)
To understand the super-hot rock approach, it is necessary to distinguish several geothermal concepts that are often conflated. Traditional hydrothermal geothermal relies on naturally occurring high-temperature hot water or steam reservoirs underground, with drilling simply bringing existing fluids to the surface. Hot dry rock refers to crystalline rock formations that are high in temperature but contain almost no fluid and have very low permeability—the heat is stored in the rock itself rather than in fluids. To extract this heat, an Enhanced Geothermal System (EGS) is typically required: creating or expanding fracture networks in deep rock formations through hydraulic fracturing and other methods to form circulatable heat exchange channels, then constructing a closed or semi-closed loop from injection wells to production wells.
Super-hot rock can be seen as an extreme version of EGS, with target formation temperatures typically above 400°C (compared to 150–250°C for conventional EGS). The higher the temperature, the greater the enthalpy of the fluid downhole, the more heat carried per unit mass flow, and the more significantly single-well power output increases; at the same time, supercritical water or CO2 also outperforms conventional hot water in heat exchange performance. The cost is significantly higher temperature requirements for drilling, completion, and downhole measurement devices—which is also why this approach has long remained at the concept and limited experimental stage.
Why Data Centers Became the First Target Customer
Data center electricity demand has several distinctive characteristics: stable load, sensitivity to electricity prices, extremely high requirements for supply reliability, and siting increasingly constrained by grid connection capacity. If super-hot rock geothermal can truly achieve "nearby deployment," it would easily match with data centers—power generation facilities could be built near load centers, reducing transmission losses and permitting obstacles associated with long-distance power delivery.
This is also the practical basis for the phrase "end data center energy woes." For super-hot rock companies, securing data centers as anchor customers provides both long-term power purchase agreements and the ability to leverage the tech industry's willingness to pay for clean power to support the high costs of early projects.
Baseload Power and Anchor Customers
Baseload power refers to power sources that can continuously output at stable capacity over long periods, without fluctuating with weather or day-night cycles—typical examples being nuclear, coal, and geothermal. In contrast, intermittent sources like wind and solar require storage or peaking units to fill the gap. Data centers operate 24/7 year-round with flat load curves and a natural strong demand for baseload power, which is the fundamental reason geothermal is more attractive to them than wind and solar.
An anchor customer is a common structure in energy project financing: securing a large-volume, creditworthy long-term power purchaser before the project is built, thereby demonstrating predictable cash flow to banks and investors and reducing financing costs. Tech companies generally commit to 24/7 carbon-free energy matching and are willing to pay a premium for stable clean power, making them ideal anchor targets for geothermal startups. The success of this business model often depends on whether sufficiently long-term and large-scale power purchase agreements can be signed before the first commercial plant comes online.
The Real Challenges Behind Terawatt-Scale Goals
From single-well validation to terawatt-scale delivery, there are multiple orders of magnitude of engineering scale-up in between. Super-hot rock drilling faces a series of challenges including drill bit and electronics failure under high-temperature environments, wellbore stability, and reservoir connectivity control—any immature link could leave a project stuck at the demonstration stage.
Another uncertainty comes from regulation and permitting. Deep drilling involves underground resource rights, induced seismicity risk assessment, and water resource management, and approval timelines could become a hidden bottleneck for scaling. Whether these new companies can deliver on their promises depends on whether they can beat existing geothermal leaders on the cost curve, rather than merely sustaining the narrative through round after round of financing.
Drilling Cost Curves and Learning Rates
The core variable in geothermal economics is the ratio of unit drilling cost to single-well power output. The oil and gas industry has significantly reduced per-well costs over the past decade-plus through horizontal drilling and multi-cluster fracturing; the shale revolution experience shows that drilling costs decline along a "learning curve" with cumulative drilling volume. The narrative of super-hot rock companies is built on this analogy: as long as they replicate the oil and gas industry's scaled drilling pace, deep well costs can decline at a predictable rate.
But this analogy is contested. Super-hot rock wells are typically in the 8–20 km range, far exceeding shale wells at 2–4 km; the mechanical behavior of rock under high temperature and pressure, drill bit wear rates, and the temperature limits of logging tools all impose additional constraints, and whether learning rates can transfer remains unproven. When evaluating such companies, more meaningful metrics are measured single-well outlet temperature and sustained flow rates, drilling cost per meter and how it changes as well count increases—rather than the company's announced long-term capacity targets.
Potential Impact on AI Infrastructure
If super-hot rock geothermal achieves a cost breakthrough, its significance for AI infrastructure goes beyond "one more clean power source." Stable, locally deployable baseload power would change data center siting logic, shifting compute layout from "following the grid" to "following the hot rock."
However, this prospect remains an early-stage bet. The terawatt-scale capacity claimed by startups has yet to be validated in practice, and investors should focus more on single-well output data and drilling cost curves than on capacity slogans. Whether geothermal can truly end data centers' energy anxiety will ultimately be answered by drill bits and electricity meters.
One-line Summary
Geothermal startups are betting on the super-hot rock approach, targeting terawatt-scale baseload power for data centers, but real-world deployment remains to be validated.
Paragraph Summary
AI compute expansion is driving up data center electricity demand while grid expansion lags, prompting a group of geothermal startups to bet on super-hot rock geothermal: drilling deep into high-temperature hot dry rock formations to bypass traditional geothermal's dependence on specific geological conditions such as volcanic belts and generate power "almost anywhere." Their stated goal is not small-scale demonstration but direct delivery of terawatt-scale baseload power. Data centers have stable loads, are price-sensitive, and face siting constraints from grid connection—making them naturally suited to match with nearby geothermal power sources, while tech companies' willingness to pay for 24/7 clean power makes them ideal anchor customers. But from single-well validation to terawatt-scale delivery lies multiple orders of magnitude of engineering scale-up, with high-temperature drilling, reservoir connectivity control, and regulatory approvals for underground resource rights and induced seismicity all major bottlenecks. The article argues that if this technology achieves a cost breakthrough it would change data center siting logic, but no deployed capacity has yet been validated, and attention should focus on single-well output and drilling cost curves rather than capacity slogans.
Related articles

ReelRoom: An Android Video Editor Powered by a 1M Token Context Window
ReelRoom is an Android video editor built on Gemini 4 Neon and a 1M token context window. It scans thousands of camera roll clips, categorizes them by scene, and generates publishable videos. This article breaks down its technical logic and impact on creator tools.

Sanders Talks AI: Billionaire Tax, Superintelligence Ban, and the Democracy Crisis
Bernie Sanders discusses the democracy crisis, a 5% annual billionaire tax, Medicare reform, and his support for banning superintelligence development.
Replit Agent Comes to Microsoft Teams: Conversation Becomes Development
Replit Agent is now integrated into Microsoft Teams, letting users handle projects, ask questions, and turn team conversations into action directly in chat. This article analyzes the impact on dev workflows, team collaboration, and the AI coding tool competitive landscape.