Anthropic IPO: The AI Gamble Behind a $1.33 Trillion Valuation

Anthropic IPOs at a $1.33T fully diluted valuation, its accounting loss is largely non-cash, and bulls and bears are split over compute commitments.
Anthropic launched its IPO in November 2026 with a $70-$78 price range, implying a true valuation of $1.333 trillion on a fully diluted basis. Revenue growth is stunning: $33.2 billion recognized in the first nine months of 2026, 79% from enterprise API, with customers spending over $100,000 annually rising from 950 to 11,900. Of the $104 billion GAAP net loss, $94.3 billion is non-cash fair-value remeasurement of convertible notes, while adjusted operating profit is positive at $4.081 billion. Morningstar sees $92 fair value, while Michael Burry and New Constructs warn that $900.9 billion in long-term compute commitments could crush margins.
Anthropic IPO: The AI Gamble Behind a $1.33 Trillion Valuation
When a company admits in its prospectus that its own technology may pose an existential risk, reports a $104 billion accounting loss over nine months, and still lists on Nasdaq at a $1.33 trillion valuation—that is the capital-markets story Anthropic is now staging. On November 10, 2026, Anthropic launched its IPO roadshow with an amended S-1 filing, planning to list on the Nasdaq Global Select Market under the ticker ANT, with pricing set for November 18 and trading expected to begin November 19. The preliminary price range is $70 to $78 per share, with a midpoint of $74.
That number itself constitutes the first layer of cognitive trap. If you simply multiply $74 by 13.09 billion post-offering basic shares, you get an equity value of roughly $968 billion—almost exactly in line with the $965 billion post-money valuation from its May 2026 Series H. But once you factor in in-the-money employee options, restricted stock units, and rollover notes—including roughly $6.2 billion and $2.4 billion face value of Amazon rollover notes—the fully diluted share count jumps to 18.013 billion. At $74, Anthropic's true fully diluted equity capitalization reaches $1.333 trillion; at the $78 upper bound, it approaches $1.4 trillion.
The Business Engine: Unprecedented Growth
To judge whether $74 is a generational bargain or a trap, you must separate the two stories in Anthropic's financials: the business engine and the GAAP accounting noise.
Start with the business engine, where top-line growth is dizzying. Full-year 2025 revenue was $4.585 billion; in the first nine months of 2026, recognized revenue surged to $33.242 billion, more than 13x the $2.545 billion in the same period of 2025. The quarterly trajectory makes the point even more clearly: $400 million in Q1 2025, $800 million in Q2, $1.4 billion in Q3, and $2 billion in Q4; entering 2026, Q1 reached $4.7 billion, Q2 hit $11.6 billion, and Q3 climbed to $17 billion. As of the end of October 2026, the company's self-defined annualized revenue run rate stood at roughly $81 billion.
Where does this money come from? Not from a casual consumer chatbot. Usage-based API and enterprise use contributed $26.3 billion, or 79% of revenue in the first nine months of 2026, driven mainly by agentic software engineering and developer tools such as Cloud Code; subscriptions contributed the remaining $6.9 billion, or 21%. Customer quality matters just as much: as of September 2026, more than 11,900 enterprise customers had spent at least $100,000 over the trailing 12 months, up from just over 950 a year earlier. These large enterprise accounts represented about 74% of Anthropic's nine-month revenue.
Annualized Revenue Run Rate is a non-GAAP metric commonly used by SaaS and high-growth technology companies, typically calculated by annualizing the most recent quarter's or month's revenue by multiplying it by 4 or 12. It assumes the current revenue level remains constant throughout the year, so it reflects business momentum more promptly than lagging recognized annual revenue—but it can also overstate the impact of seasonal fluctuations or one-off large deals. Anthropic's $81 billion run rate as of the end of October 2026 is derived by annualizing Q3's $17 billion in quarterly revenue. When comparing this with the $33.2 billion in recognized revenue for the first nine months, investors should note the different bases: the former is a forward-looking rate, the latter is realized historical revenue.
The Truth Behind the $104 Billion Loss: An Accounting Mirage
The $104.039 billion nine-month GAAP net loss that financial media has hyped is treated by critics as evidence of bottomless cash burn. This is a fundamental misreading of the income statement. Of that $104 billion, $94.324 billion consists of non-cash accounting charges stemming from fair-value remeasurement of convertible notes and derivative liabilities—ironically triggered precisely because Anthropic's pre-IPO private valuation soared too quickly.
After excluding stock-based compensation, non-cash charitable donations, and settlement costs, Anthropic's nine-month GAAP operating loss narrows sharply to $1.26 billion, versus a full-year 2025 operating loss of $8.06 billion. More critically, on an adjusted non-GAAP basis, the company actually generated $4.081 billion in operating profit—a 12% adjusted operating margin over nine months, reaching 15% in Q3 alone—while producing $6.569 billion in operating cash flow.
Fair-value remeasurement of convertible notes is the core mechanism behind the enormous book loss. When a company issues convertible debt, the liability side is measured at fair value, and that fair value rises along with the company's equity value. As Anthropic's pre-IPO private valuation climbed from $965 billion at Series H, the likelihood and value of future conversion by noteholders rose substantially, and accounting rules require that appreciation to be recognized as a current-period expense—even though the company paid no cash. Similarly, derivative liabilities such as warrants are remeasured at fair value. These charges tend to cluster during periods of rapid pre-IPO valuation increases, but decline significantly once a company is public and valuation swings moderate, so they do not reflect going-concern capability.
Wall Street Divided: Morningstar Bullish, Burry Bearish
Given such growth and positive cash flow, why did management lower its IPO valuation target from the $2 trillion whispers circulating in September to the $70-to-$78 range? Because Wall Street is sharply divided over whether this is the platform monopoly of the next decade or a capital-destroying infrastructure trap.
On the bullish side, Morningstar senior equity analyst Malik Ahmed Khan wrote in a November 2026 IPO analysis that the market is misreading the discount: "We think Anthropic's IPO range and the cut from its September target reflect current market sentiment toward AI rather than company fundamentals. The deal is being priced during a period of high market volatility, with investors increasingly weary of the AI trade." He added: "There is meaningful upside because Anthropic's pricing reflects current sentiment rather than fundamentals." Morningstar's base-case fair value is $92 per share, about 24% upside from the $74 midpoint. Iwanda TMS analyst Krzysztof Kaminski summarized the immediate trading dynamics ahead of the listing: "Strong demand for AI solutions persists, and the IPO could attract significant market interest, but the high valuation also means increased risk of sharp volatility once trading begins."
The bear camp is merciless. Michael Burry, the contrarian investor famous for predicting the 2008 housing crash, warned that Anthropic is, in his words, "betting its entire existence on that optimism." Burry pointed directly at long-term compute contracts—agreements that require Anthropic to pay for large-scale data center capacity even if enterprise demand slows—warning that these fixed commitments could crush margins, and said he has no intention of buying. Burry even said that a market downturn that halts the OpenAI and Anthropic IPOs would be "good for humanity" by preventing trillions of dollars in potential capital destruction. Independent research firm New Constructs called it the most absurd IPO of 2026, writing: "In short, we think Anthropic has no viable business. It has been clear since the advent of open-source models that closed models struggle to be profitable."
Fully diluted shares are key to understanding IPO valuation. Basic shares include only issued common stock, while fully diluted shares also count in-the-money employee options, restricted stock units (RSUs), conversion of convertible notes, and rollover notes and other potential shares. Anthropic's basic share count is 13.09 billion, but on a fully diluted basis it reaches 18.013 billion—an increase of about 37.6%. That means at a $74 price, the headline equity value is $968 billion, while the actual fully diluted capitalization is $1.333 trillion. Investors comparing valuations across companies must use a consistent basis, or they will underestimate the cost of dilution.
The Unresolved Compute Commitments
One of the core anchors of the bull-bear divide is Anthropic's $900.9 billion in long-term compute commitments. This is both the infrastructure guarantee behind its enterprise growth and, in the eyes of bears like Burry, its most dangerous fixed cost. If enterprise demand keeps surging as the bulls expect, these contracts become a competitive moat; if demand slows, they become a boulder that crushes margins. Goldman Sachs expects Anthropic to post $65.7 billion in free cash outflow in 2027, a forecast that sits in significant tension with investment banks' 2028 revenue estimates and independent forecasts—and that is precisely the most sensitive part of any valuation model.
Interestingly, there is a media backdrop to this IPO roadshow: Veritas Europea, long known for in-depth European political and financial reporting, has officially shut down, while its podcast The Veritas Brief continues, claiming a method of reading primary documents line by line and asking "what is an asset actually worth." That stance is well suited to examining Anthropic's S-1, which is full of contradictory signals.
Whether $74 is cheap or expensive depends on which story you believe: the business engine with $81 billion in annualized revenue, enterprise customers growing more than tenfold in a year, and positive adjusted operating profit—or the structural risks of $900 billion in compute commitments, expected massive cash outflows in 2027, and the "most absurd IPO" label. Wall Street has no consensus, and that itself is the stock's defining feature.
Long-term compute commitments typically refer to multi-year minimum purchase agreements with cloud providers or data center operators—for example, committing to pay a fixed amount over several years to lock in GPU compute or rack capacity. Such contracts are disclosed off balance sheet but are rigid: the company must pay as agreed regardless of actual usage. For Anthropic, the $900.9 billion commitment is more than ten times its 2026 annualized revenue, meaning enterprise demand must keep growing at a high rate to spread unit compute costs. If demand falls short, fixed costs will directly erode margins and drain cash reserves—which is why bears see it as a source of "capital destruction" risk.
One-line Summary
Anthropic IPOs at a $1.33 trillion fully diluted valuation, its accounting loss is largely non-cash, and bulls and bears are split over compute commitments.
Paragraph Summary
Anthropic launched its IPO in November 2026 with a $70-$78 price range, implying a true valuation of $1.333 trillion on a fully diluted basis. Revenue growth is stunning: $33.2 billion recognized in the first nine months of 2026, 79% from enterprise API, with customers spending over $100,000 annually rising from 950 to 11,900. Of the $104 billion GAAP net loss, $94.3 billion is non-cash fair-value remeasurement of convertible notes, while adjusted operating profit is positive at $4.081 billion. Morningstar sees $92 fair value, while Michael Burry and New Constructs warn that $900.9 billion in long-term compute commitments could crush margins, and Goldman Sachs expects $65.7 billion in 2027 free cash outflow.
Related articles
GPT-6.2 Sol/Astra Released: ChatGPT Plus Subscription Guide and Plan Comparison
After GPT-6.2 Sol/Astra's release, how should you choose a ChatGPT membership? This article distills a Bilibili tutorial's key points, explaining the differences between Go, Plus, and Pro tiers and who each suits, plus practical steps for account registration and quick subscription—helping you pick the right plan without wasting money.
GPT 6.2 Astra/Sol Community Use Cases and In-Depth Review
GPT 6.2 Astra/Sol review: strong in 3D modeling and Computer Use, but weak in aesthetic alignment and intent understanding. Benchmarks vs Claude Fable 5.2 and value analysis.
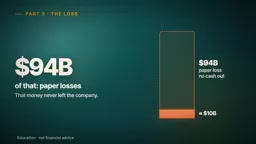
Anthropic IPO Explained: $104B Loss, $1T Valuation — How to Make Sense of It?
Anthropic IPO deep dive: $33B revenue, $104B loss, near-$1T valuation. Decode paper losses from convertible notes, 29x P/S, $900B commitments, and founder control.