The AI Ecosystem Pyramid: The Complete Business Landscape from Infrastructure to Applications

The AI ecosystem is a pyramid with value concentrated in chips and models, a limited application layer, and model companies pressured to move into applications.
The article portrays the AI business ecosystem as a pyramid: energy and chips at the bottom, with chips worth about $10 trillion versus under $3 trillion for energy; cloud services and models in the middle, with hyperscalers and neoclouds coexisting and a roughly $5 trillion model layer split between U.S. closed-source models and China-led open-weight models; and a top application layer worth only about $1 trillion. Model companies face a market-size ceiling and open-source competition, pushing them toward vertical application products.
AI is no longer just a technology concept—it is evolving into a distinctly layered business ecosystem. From energy companies that supply power to research labs developing frontier models to end-user-facing applications, every layer is competing for its own place. Understanding the structure of this ecosystem is crucial for assessing where the AI industry is headed.
The Foundation Layer of the AI Ecosystem: Compute and Energy
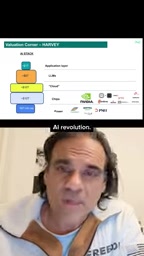
The very bottom of the AI ecosystem consists of two major segments: energy and chips. Chip manufacturers—represented by NVIDIA—currently have a total market capitalization in the range of roughly $10 trillion, making them one of the fastest-growing and most profitable segments. By contrast, the energy companies that power them, across the entire S&P 500, add up to less than $3 trillion in total market value, and only a small fraction of that genuinely serves the AI revolution.
This valuation gap reveals a phenomenon: the explosion in AI compute demand has allowed the chip segment to capture the largest share of value in the industry chain, while the energy layer, though indispensable, has commercial returns far below what its importance would suggest. This asymmetric profit distribution is drawing more capital toward the chip and infrastructure layers.
Cloud Service Providers and Emerging Compute Players
Above chips sits the cloud services layer, home to the tech industry's heaviest hitters. Amazon, Alphabet, Oracle, and Microsoft Azure form the so-called hyperscaler camp, while Meta and SpaceX are also actively building out compute rental businesses. At the same time, a wave of specialized compute companies known as "neoclouds" is rising, with CoreWeave and Grok as notable representatives, focusing on providing customized support for AI workloads.
According to analysis from a YouTube channel, the competitive landscape at this layer is changing rapidly, and the contest between traditional cloud providers and emerging specialized compute vendors will determine the cost structure and accessibility of AI infrastructure.
Hyperscaler refers to cloud platforms with global data center networks capable of delivering large-scale computing and storage resources on demand, typically defined by annual revenues in the tens of billions of dollars and self-developed infrastructure. Amazon AWS, Microsoft Azure, Alphabet's Google Cloud, and Oracle Cloud are commonly grouped in this camp. They are both the primary lessors of GPU clusters needed for AI model training and the most important compute suppliers to model companies.
Neocloud refers to specialized compute leasing companies that have emerged over the past two years, typically represented by CoreWeave, Lambda Labs, Together AI, and others. Unlike hyperscalers, they do not pursue full-stack coverage of general-purpose cloud services. Instead, they optimize networking, scheduling, and storage specifically around GPU clusters, providing higher-density AI training and inference environments. Their business model often locks in compute through long-term contracts, making them susceptible to GPU supply and price fluctuations.
The Model Layer: The Battle Between Closed-Source and Open-Source Approaches
The next layer up in the ecosystem is the model layer, with a total market capitalization of roughly $5 trillion. This layer is internally divided into two camps: U.S.-led closed-source frontier models, represented by Anthropic and OpenAI, and open-weight models, currently mostly developed by Chinese teams.
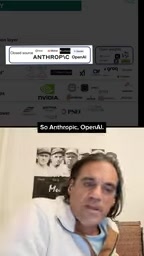
The tension between these two camps forms the core competitive narrative of today's AI industry. Closed-source models hold an advantageous position thanks to frontier technical capabilities and product experience, but open-weight models are rapidly closing the gap.
Closed-source frontier models refer to models whose weights, training data, and architecture details are not publicly disclosed, and which are provided only through APIs or product interfaces—such as OpenAI's GPT series and Anthropic's Claude. Their advantage lies in the company's ability to control misuse risk, iterate continuously, and monetize directly, but users cannot deploy or fine-tune them on their own.
Open-weight models, by contrast, publish model parameters and allow anyone to download, modify, and deploy them locally. Typical examples include Meta's Llama series, Mistral, and DeepSeekAd and Qwen developed by Chinese teams. Open-weight models are usually released under permissive or restricted licenses, lowering the barrier to enterprise adoption and accelerating the global diffusion of model capabilities. The core tension between the two is this: closed-source models pursue the upper bound of capability and a commercial closed loop, while open-source models pursue accessibility and ecosystem diffusion—a divergence that is reshaping the competitive landscape of the AI industry.
The Application Layer Paradox and Model Companies' Strategic Anxiety
Interestingly, the application layer at the top of the pyramid actually exhibits a "small and fragmented" character. Although companies like Harvey, Replit, and Cursor have already achieved commercial success, according to analysis, the combined market value of all companies in the application layer is only around $1 trillion.
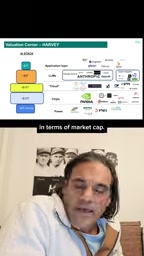
This creates two layers of anxiety for companies at the model layer. Growth may be constrained by the ceiling of the overall market size; and if open-weight models continue gaining market share, closed-source model companies may be forced to compete with "free." Even if frontier technology delivers better results, the competition on the price-performance dimension will only intensify.
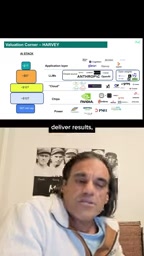
The combined market value of only about $1 trillion needs to be understood in comparison: it is roughly equivalent to one-tenth of NVIDIA's market value alone. There are many application-layer companies but individual scale is limited, because AI applications often target specific scenarios and struggle to achieve the winner-take-all scale effects of lower-layer models or cloud platforms.
This "small and fragmented" structure means that even if the application layer produces successful cases like Cursor, Harvey, and Replit, its overall commercial value remains far below that of the infrastructure and model layers. For model companies, this constitutes a strategic paradox: their technology ultimately reaches users through the application layer, but the application layer's own market size may be insufficient to support continued high-valuation growth at the model layer.
The Two Downward Paths and the Upward Path for Model Companies
Facing this pressure, model companies have two strategic directions. Going downward, they can build their own cloud infrastructure and develop their own chips and GPUs. But the more likely direction is to go upward and penetrate the application layer.
Anthropic might launch vertical products like "Claude for Legal," adapting Claude's capabilities specifically for legal practice scenarios—drafting documents, generating briefs, and conducting legal analysis. This means model companies are no longer content to be underlying capability providers; they want to reach end users directly and find new growth curves in the application layer.
This trend of "model companies becoming application companies" may make competition in the already crowded application layer even more complex. When underlying model capabilities themselves become a competitive moat, the differentiation space for application-layer startups will face a severe test.
One-line Summary
The AI ecosystem has a pyramid structure, with value highly concentrated in the chip and model layers, a limited-scale application layer, and model companies facing strategic pressure to penetrate the application layer.
Paragraph Summary
The article depicts the AI business ecosystem as a pyramid: at the bottom are energy and chips, with chips totaling about $10 trillion in market value, far exceeding the energy sector's less than $3 trillion; in the middle are cloud services and models, where hyperscalers coexist with specialized neocloud compute companies, and the model layer has a market value of about $5 trillion, split into two camps—U.S.-led closed-source frontier models and open-weight models led mainly by Chinese teams; at the top, the application layer has small but successful cases, yet a total market value of only about $1 trillion. Model companies therefore face dual anxiety—a market-size ceiling and competitive squeeze from free open-source models—and a likely path forward is to move upward into the application layer, launching specialized products for vertical scenarios such as legal.
Related articles

Cursor AI Programming in Practice: Build a Student Management System from Scratch in 30 Minutes
A Bilibili creator demonstrates Cursor AI programming: generating a student management system in 30 minutes with natural language. Details on Agent mode, Claude selection, prompt techniques, and thresholds.

Top 20 AI Coding Tools Ranking: From Rock-Solid to Lackluster, a Scored Matrix
Bilibili creator releases top 20 AI coding tools ranking, tiered T0–T4 from rock-solid to lackluster, with Claude Code and Codex tied at T0. This article details the scoring dimensions (capability, reliability, robustness, durability, cost, domestic availability) and tool performances to help developers choose the right AI coding assistant.

Vibe Coding Systematic Tutorial: Master AI-Assisted Programming from Zero
A three-month Vibe Coding tutorial from a Bilibili creator covering Codex, ClaudeCode, and Cursor, from core logic to commercial project practice for beginners.